Workers comp vs general liability is the wrong way to frame it. Workers compensation responds when someone who counts as your employee is hurt doing your work. General liability responds when you are legally liable for injuring someone else or damaging their property. They are not competing products, and for most contractors with employees the working answer is both, because they answer completely different risks. There are real exceptions, including a California owner-operator who qualifies for an exemption and a Texas contractor with no employees and no contract requiring cover. ContractorsInsured.net is Pascal Burke Insurance Brokerage, Inc., licensed in California (#6015321) and Texas (#3305690). We place both policies for contractors in both states and issue the certificate once coverage is bound.
The one-sentence difference
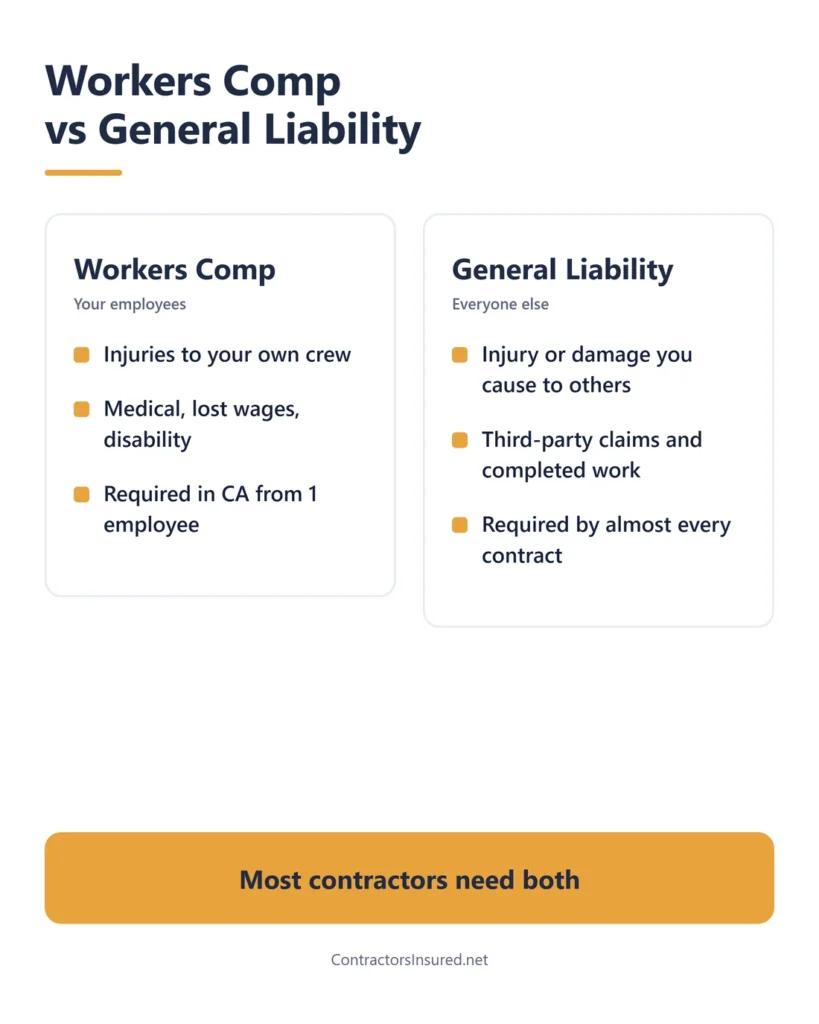
In brief: Workers compensation covers work injuries to people who count as your employees. General liability covers your legal liability for injury and damage to third parties. Every other distinction on this page hangs off that one.
Contractors mix these up often, and the confusion is understandable, because both get demanded by the same general contractor on the same certificate. But they respond to opposite sides of the same jobsite.
As a first sort: if the injured person works for you, start with workers compensation. If the injured person is a homeowner, a passer-by or another trade’s employee, or if the damaged property belongs to someone else, start with general liability.
Treat that as a way of orienting yourself rather than a coverage determination. Who counts as your employee is set by law rather than by whether you run them through payroll, and both states reach further than people expect. California recognizes express, implied, oral and written employment relationships, and Texas can in some circumstances treat a subcontractor’s workers as the general contractor’s employees for workers compensation purposes. On the other side, general liability does not automatically cover every third party or every item of their property: a claim still has to fall inside the insuring agreement and outside the exclusions.
Side by side
| Workers compensation | General liability | |
|---|---|---|
| Who it protects | Your employees, and you as the employer | You, against liability to third parties |
| What triggers a claim | A work-related injury or illness to someone who counts as your employee | Bodily injury or property damage to a third party that you are liable for |
| Typical claim | A framer falls and breaks a wrist | You crack a client’s tile floor, or a visitor trips over your cable |
| Who requires it | State law in California from your first employee. Optional for most private employers in Texas, but often required by contract | Rarely state-mandated. Required by license in some cases, and commonly required by contract |
| What it does not cover | People who are not your employees, and damage to property | Direct employee injury claims, and generally the cost of redoing your own defective work |
| How it is priced | Per $100 of payroll, by trade classification, adjusted for claims history | Trade, revenue, limits, location, payroll, subcontracted work and claims history |
| What a GC asks for | A certificate, sometimes a waiver of subrogation | A certificate, additional insured status, specified limits |
What workers comp covers
In brief: Medical treatment for the work injury with no deductible or co-pay charged to the worker, partial wage replacement while they cannot work, permanent disability benefits, and death benefits.
The important structural point is that workers compensation is a no-fault system. Your employee does not have to prove you did anything wrong to receive benefits, and in exchange the system is generally the exclusive remedy against you for that injury. That trade is the reason the coverage exists.
Who actually has to carry it, and the exemptions available to owner-operators, are covered properly in our guide to workers comp for small construction businesses. If you work in Texas, the non-subscriber rules deserve their own read in our Texas workers comp guide.
What general liability covers
In brief: Third-party bodily injury, third-party property damage, and injury or damage arising from work you have already completed. It also covers personal and advertising injury, which comes up less often for contractors but does come up.
The part contractors underrate is products and completed operations. This can respond where injury or property damage arises out of work you have already finished, provided the claim meets the policy’s requirements and no exclusion applies. A deck you built eighteen months ago fails and someone is hurt: that falls to be considered under completed operations rather than as a claim on the job you are working today. It is also why general contractors insist your coverage stays in force after practical completion rather than lapsing the day you leave. Note that it is the resulting injury or damage that is in question, not the mere fact that the work failed.
What general liability does not do is act as a warranty on your workmanship. As a general rule it does not pay to rip out and redo your own defective work, because that is treated as a business risk you control rather than a fortuity. It can respond to the damage that defective work causes to other property, which is a genuinely different thing. The standard exclusions also carry a subcontractor exception, and endorsements and applicable state law can change the result, so your own policy wording governs.
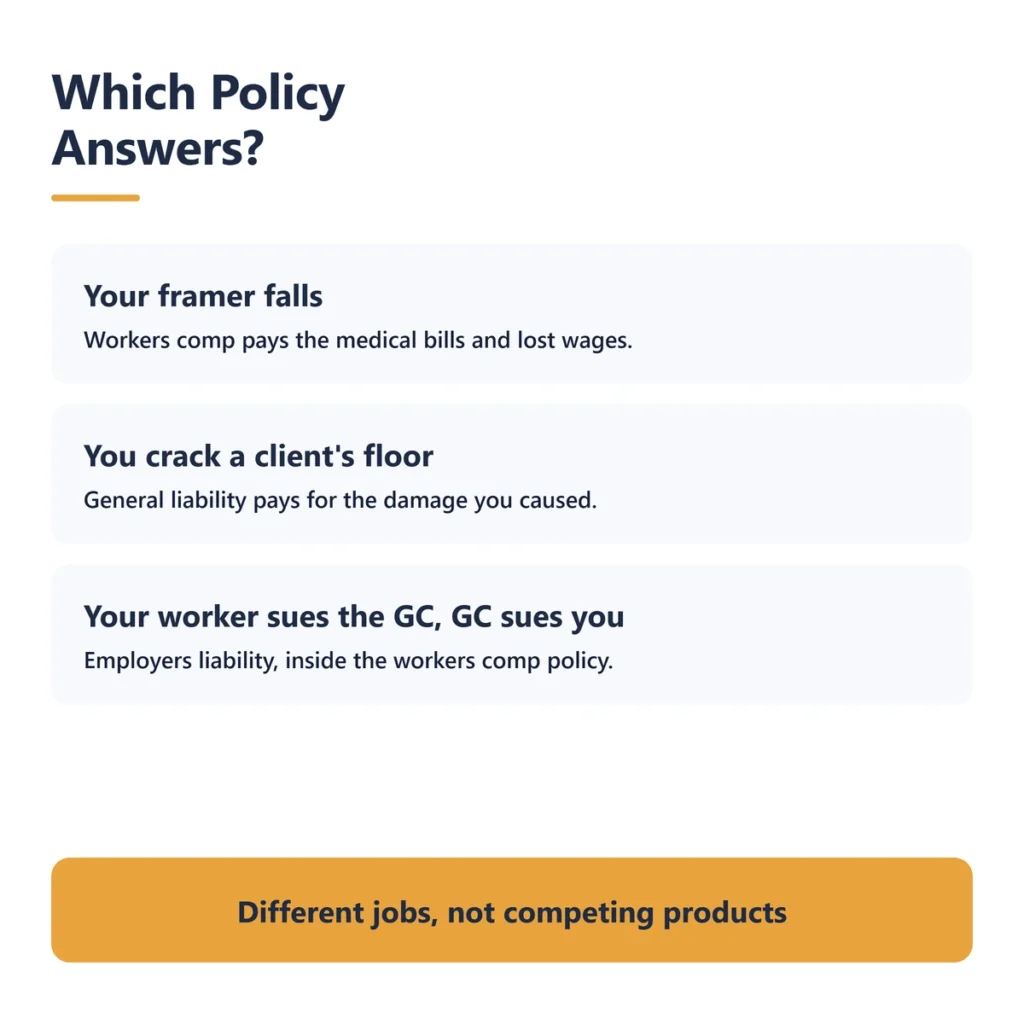
Three jobsite scenarios, and which policy answers
In brief: Two of these are clean, one shows exactly where the two products meet. Treat them as illustrations of how each policy is meant to work rather than as coverage determinations.
1. Your framer falls off a ladder and breaks a wrist. This is workers compensation territory. He is your employee and the injury arose out of the work, so that is the policy that responds to his medical treatment and part of his lost wages, assuming the claim is compensable. General liability is not the policy in point.
2. You drop a load of tile and crack the homeowner’s marble floor. This is general liability territory. The damaged property belongs to a third party and the question is your legal liability for it, subject to the policy’s exclusions, including those dealing with property in your care, custody or control. Workers compensation is not the policy in point.
3. Your employee is hurt, collects workers compensation, then sues the general contractor. The general contractor looks to pass that liability down to you. This is the one people do not see coming, and which policy responds depends on how the claim reaches you.
Where the general contractor brings a non-contractual claim for contribution or indemnity because your employee sued them, that is the classic third-party-over claim, and employers liability, which sits inside the workers compensation policy rather than alongside it, is usually the coverage in point.
Where the claim instead rests on an indemnity clause in your subcontract, the analysis usually starts with your general liability policy. Standard employers liability excludes liability assumed under a contract, apart from a narrow exception, while a standard general liability policy preserves cover for liability assumed under a qualifying insured contract. Anti-indemnity statutes and action-over endorsements can move the answer in either direction.
Be precise about what employers liability is, because it is often described far too broadly. It is not a catch-all for anything outside the comp system. It covers specified employment-related bodily injury liabilities that fall outside the ordinary benefit schedule, subject to its own conditions and exclusions. The practical point is not which box the claim lands in. It is that this route down the contractual chain exists at all, which is why carrying both policies and reading the indemnity clause both matter.
“Every contractor understands the ladder and the broken floor. Far fewer have thought about the third scenario, where the general contractor gets sued and passes it straight down the chain.” Pascal Burke, Licensed Insurance Broker
Need both policies quoted together?
Send us your payroll, your trades and your contract requirements. We will price workers comp and general liability side by side.
The gap between them, and what falls in it
In brief: Carrying both still leaves real holes. Your tools, your truck, your own defective workmanship, and any design or professional exposure all sit outside this pair.
A two-policy stack is the right foundation, not a complete program. What neither policy handles:
- Your tools and equipment. That is inland marine, sometimes called contractor’s equipment coverage. Neither general liability nor workers comp pays when your kit is stolen off a site.
- Your vehicles. Commercial auto. A general liability policy will not respond to a collision in your work truck.
- Redoing your own defective work. As a general rule general liability responds to resulting damage to other property rather than to the cost of putting your own faulty work right. The standard exclusions carry a subcontractor exception, and endorsements and state law can change the answer, so read your own wording.
- Design and professional errors. If you are design-build or you give advice a client relies on, professional liability is a separate conversation.
Being straight about the gaps is more useful than pretending two policies cover everything. If a contract requires more than this pair, it is often asking for one of the four above, and commonly also for umbrella or excess liability, builders risk, or pollution coverage depending on the work.
Which one does the law require?
In brief: Workers comp is the one the state cares about. General liability is the one the contract cares about.
California requires workers compensation of every employer from the first employee under Labor Code section 3700, and five contractor classifications must carry it even with no employees at all. Texas leaves workers compensation optional for most private employers. The statutory exception is narrow: a private employer that enters a building or construction contract with a governmental entity must cover the employees working on that project. A requirement in a private subcontract is a contractual obligation you have taken on, not an exception to the state rule, though it binds you just as firmly.
General liability is generally not state-mandated for contractors. It is required at license level in some cases, including CSLB licensees registered as an LLC in California, and several Texas licenses carry their own insurance minimums. Beyond licensing, the contract is what usually forces the issue, and insurance clauses are standard on commercial work. Full detail on the workers comp side is in our small construction business guide.
What it costs to carry both
In brief: Published figures put construction workers comp around $175 per month and contractor general liability somewhere between about $89 and $337 per month depending on whose figure you read and what it measures.
Three reference points, and it matters what population each one describes:
- Workers compensation, about $175 per month or $2,101 per year. Insureon’s published figure for its construction and contracting customers who bought the coverage, drawn from a book of more than 40,000 construction small businesses where most have fewer than five employees. Within that group, 44 percent pay under $150 per month. Insureon’s methodology describes these figures as medians of policies purchased.
- General liability, about $89 per month, or $1,069 per year. Insureon’s published figure for its construction and contracting customers at $1 million per occurrence and $2 million aggregate with a $500 deductible.
- General liability, about $337 per month. MoneyGeek’s modeled national contractor figure at the same $1 million and $2 million limits for a one to four person business.
Do not read the last two as a contradiction. One reflects what a brokerage’s actual customers bought; the other is a modeled price for a standardized business, built across 45 contractor industries and all states. They measure different things, which is exactly why quoted numbers vary so much. Full breakdowns are in our guides to workers comp cost and general liability cost.
What a general contractor actually asks you for
In brief: Both policies, a certificate evidencing them, additional insured status on the general liability, often a waiver of subrogation, and specified limits. This is the practical reason most contractors end up carrying both rather than choosing between them.
The request usually arrives as a paragraph in a subcontract rather than a question, and it typically covers:
- Both policies in force, with limits at least matching the contract. One million per occurrence and two million aggregate is a common general liability requirement, and it is the limit 92 percent of one large brokerage’s construction customers buy.
- A certificate of insurance evidencing them. Worth knowing that a certificate is evidence of coverage, not coverage itself. See our guide to the certificate of insurance.
- Additional insured status on the general liability. That has to come from the policy’s own provisions or an endorsement, which may be a blanket endorsement rather than one naming the general contractor specifically. Being listed on a certificate is not the same as being added to the policy.
- A waiver of subrogation, often on both policies, which stops your insurer pursuing the general contractor after paying a claim.
If a contract is holding up your start date, send us the insurance clause rather than guessing at it. Matching the wording exactly is usually faster than going back and forth over a certificate that does not quite comply.
Frequently asked questions
What is the difference between workers comp and general liability?
Workers compensation covers work injuries to people who count as your employees, which is set by law rather than by whether you run them through payroll. General liability covers your legal liability for injury and damage to third parties, including injury or damage arising out of work you have already completed. As a first sort, if the injured person works for you start with workers comp, and if it is a homeowner, a passer-by, another trade or someone else’s property start with general liability.
Do contractors need both workers comp and general liability?
For most contractors with employees, yes. They answer completely different risks, so one does not substitute for the other, though a California owner-operator with an exemption or a Texas contractor with no employees and no contractual requirement may not need both. Workers compensation is required by state law in California from your first employee, while general liability is rarely state-mandated but is commonly required by commercial contracts. A general contractor asking for your certificate will typically expect to see both policies on it before letting you start.
Does general liability cover employee injuries?
No. General liability excludes injury to your own employees, which is precisely the gap workers compensation fills. A direct claim by an injured employee is not a general liability matter, though liability you have assumed under a qualifying insured contract can be treated differently, which is what makes the third-party-over situation worth understanding. The one related piece is employers liability, which sits inside the workers compensation policy and covers specified employment-related injury liabilities falling outside the ordinary benefit schedule, subject to its own conditions and exclusions.
Does workers comp cover damage to a customer's property?
No. The workers compensation side of the policy deals with employee injury, not with damage to property. If you damage a client’s floor, cabinetry or landscaping, that is a general liability question rather than a workers compensation one. It also does not respond to injuries to people who are not your employees, so a homeowner hurt on your site falls on the general liability side too. The one adjacent piece is employers liability, which sits inside the same policy and covers specified employment-related injury liabilities rather than property damage.
Is general liability required by law for contractors?
Generally not by state law, though there are licence-level exceptions. California requires liability insurance of CSLB licensees registered as an LLC, and several Texas licences carry their own insurance minimums. In practice the requirement usually comes from your contract rather than the state, and one million per occurrence with two million aggregate is the limit most commonly specified.
What is employers liability, and is it the same as general liability?
No, they are different. Employers liability sits inside the workers compensation policy and covers specified employment-related bodily injury liabilities that fall outside the ordinary benefit schedule, subject to its own conditions and exclusions. The classic construction example is a third-party-over claim, where your injured employee sues the general contractor and the general contractor then brings a non-contractual claim against you. Where the general contractor’s claim instead rests on an indemnity clause in your subcontract, the analysis usually starts with your general liability policy, because standard employers liability excludes liability assumed under a contract. General liability is a separate policy covering injury and damage to third parties.
What does neither policy cover?
Your tools and equipment, which is inland marine coverage. Your vehicles, which is commercial auto. As a general rule the cost of redoing your own defective work, though general liability may respond to resulting damage to other property, and a standard subcontractor exception can preserve cover for damage to your completed work itself where a subcontractor performed it. Policy wording governs. And design or professional errors, which need professional liability. Carrying both policies is the right foundation rather than a complete insurance programme.
How much does it cost to carry both?
Published figures put construction workers compensation at about $175 per month, or $2,101 per year, across one brokerage’s construction customers who bought the coverage. For general liability the same brokerage reports about $89 per month at one million and two million limits, while MoneyGeek’s modelled national contractor figure at the same limits is about $337 per month. Those two are not contradictory: one reflects policies actually purchased and the other is a modelled standard quote, so they measure different things.
Get both policies priced together
Quoting workers compensation and general liability at the same time is usually faster and produces a cleaner certificate, because the same payroll and trade information drives both. We are a licensed brokerage in California and Texas, we shop multiple carriers for construction risks, and we issue the certificate once coverage is bound. See our overviews of workers compensation and general liability, or start below.
This guide is general information for contractors in California and Texas, not legal advice or a coverage determination. Whether any particular claim is covered depends on your policy wording, the endorsements on it, the facts, and applicable state law.
Written and reviewed by Pascal Burke, Licensed Insurance Broker and founder of ContractorsInsured.net. Insurance brokerage services are provided by Pascal Burke Insurance Brokerage, Inc., licensed in California (#6015321) and Texas (#3305690).