Workers compensation is priced on your payroll, not your revenue. The bill is roughly your payroll divided by 100, multiplied by a rate set for each trade, multiplied by your claims history. That is why two contractors with identical revenue can pay very different premiums, and why your trade classification and your carrier's own filed rates both matter more than most contractors expect. Right now California and Texas are moving in opposite directions: California's advisory rate rises on September 1, while Texas advisory loss costs already fell on July 1. ContractorsInsured.net is Pascal Burke Insurance Brokerage, Inc., licensed in California (#6015321) and Texas (#3305690). We price workers comp for contractors in both states against your actual payroll and class codes, and issue the certificate once coverage is bound.
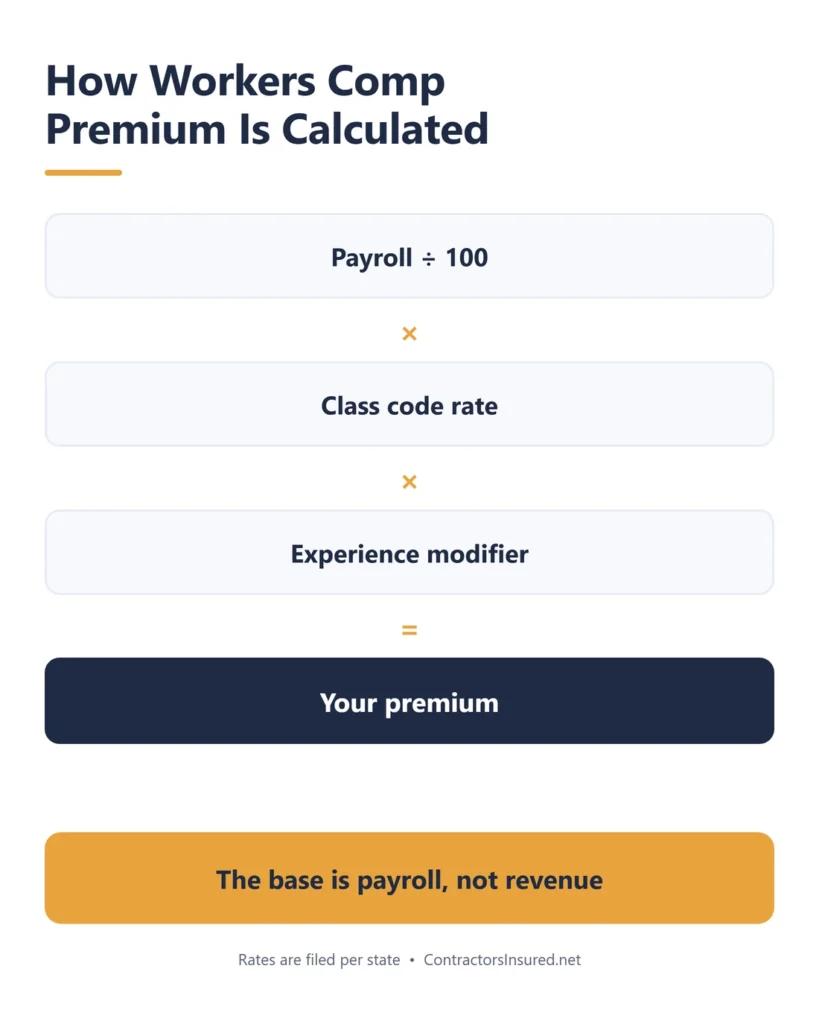
How workers comp premium is actually calculated
In brief: Take your annual payroll, divide by 100, multiply by the rate for your trade classification, then multiply by your experience modifier. Other adjustments follow, but that is the engine, and the base is payroll rather than revenue.
Written out, the calculation for a single classification is:
(Payroll ÷ 100) × class code rate × experience modifier = your premium
Each input comes from somewhere different, and knowing which is which tells you where you have leverage:
-
Payroll is yours, reported by classification and verified at your annual audit. This is a common place for estimates to drift, because payroll is projected at the start of the year and trued up at the end.
-
The class code rate reflects how dangerous the work is. The classification system and the advisory values come from the WCIRB in California and from NCCI in Texas, but the rate you are actually charged is filed by your insurer, not by either bureau. The two classification systems are not interchangeable, so a code you were quoted in Texas does not translate to a California rate.
-
The experience modifier compares your claims history to the average for your trade. More on that below.
-
Where several classifications apply, each is calculated separately and the results are added together before the modifier is applied. Expense constants, assessments and other charges then sit on top, so this gives you the shape of the bill rather than the final invoice.
The single most useful thing to understand is the base. Because premium is driven by payroll, it moves with your crew rather than with your turnover. Take on three more framers and the number goes up whether or not the jobs were profitable. Subcontract the same work to a sub who carries their own coverage and that payroll can generally be excluded, provided you can evidence their coverage for the dates worked and the relationship is genuinely an independent one. Coverage evidence alone does not settle whether the workers count as the sub’s employees or yours, which is a separate test in both states, which is the whole reason the uninsured subcontractor problem costs so much at audit.
What contractors actually pay
In brief: Published figures put construction workers compensation around $175 per month on one large brokerage’s book, against about $54 per month across all industries. The spread within construction is very wide, so treat any average as orientation rather than a quote.
Insureon reports that construction businesses and contractors buying workers compensation through it pay about $175 per month, or $2,101 per year. Within that same population, 44 percent pay under $150 per month and 69 percent pay under $300. For contrast, Insureon puts the figure across all its small business customers, most of whom are not on jobsites, at about $54 per month. Its methodology describes these as medians of policies actually purchased rather than arithmetic averages, which is worth knowing before you compare them with a modelled quote.
Read those numbers carefully, because the population matters more than the figure. That $175 reflects policies actually bought by one brokerage’s construction customers, from a book of more than 40,000 construction small businesses where most have fewer than five employees. It is not a standardised quote for a standard business, and it blends a two-person finish carpentry outfit with a roofing crew. The gap between construction at $175 and the all-industry figure at $54 is the real signal. That $54 covers Insureon’s small-business customers across every industry, not an office-only group, so read it as construction sitting well above the general run of small businesses rather than as a like-for-like comparison with an office. The usual explanation is construction’s heavier injury exposure, which is consistent with how classifications are rated, though these two figures alone do not prove it.
“Contractors ask what the average is, and here it is close to useless. A drywall crew and a roofing crew are both construction, and they are not remotely the same risk. Your class code tells you more than any published average will.” Pascal Burke, Licensed Insurance Broker
Why your trade moves the number most
In brief: Classification is one of the largest levers in the formula, and misclassification can be an expensive error. It is also easy to leave sitting quietly wrong for years, because nothing prompts a review.
Rates are set per classification because loss experience differs enormously between trades. Roof work carries fall exposure as a matter of course, so roofing is consistently among the most expensive construction classifications, and ground-level finishing trades sit well below it. Do not assume it is the single highest rated classification everywhere, though. In Texas’s July 2026 advisory loss costs, roofing sits at 1.946 per $100 of payroll while several other classifications are rated higher. Classification systems and advisory values differ by state, and insurers apply their own multipliers on top.
What is worth being precise about is who sets the number you are charged. Both California and Texas publish advisory figures rather than mandatory rates. In California the WCIRB files advisory pure premium rates that the Insurance Commissioner approves, and insurers then file their own rates. In Texas, carriers must use either their own filed classification relativities or NCCI’s advisory loss costs. In both states the published figure is a benchmark the industry prices against, not a price list. Two carriers can quote the same class code very differently.
The practical consequence is that a published per-classification rate is not what you will be charged, and you should be sceptical of any page that presents one as though it were. What is worth checking is whether the classification on your own policy actually matches the work your crews perform. If a general classification has been applied to work that belongs in a cheaper one, you have been overpaying quietly. If the reverse is true, you are exposed at audit.
Not sure your class codes are right?
Send us your current policy and payroll split. We will price it properly against your actual trades in California and Texas.
Get a workers comp quote Request a COI
The 2026 rate changes, and what they mean for your renewal
In brief: California’s advisory pure premium rate rises 6.6 percent for policies incepting on or after September 1, 2026. Texas advisory loss costs fell 3.8 percent on July 1, 2026. Neither figure is a change to anyone’s actual bill, and it is important to understand why.
|
What changed |
Direction |
Effective |
|---|---|---|
|
California advisory pure premium rate |
Up 6.6 percent, to an average of about $1.65 per $100 of payroll |
September 1, 2026 |
|
Texas NCCI advisory loss costs |
Down 3.8 percent |
July 1, 2026 |
|
California construction dual-wage thresholds |
Up $2 to $5 per hour on all 16 classification families |
September 1, 2026 |
On the California decision: the Insurance Commissioner issued it on July 10, 2026, approving advisory pure premium rates averaging $1.65 per $100 of payroll for policies incepting on or after September 1. That is 6.6 percent above the approved September 2025 rates. Worth noting is that the WCIRB had filed for 10.4 percent and was approved at 6.6. The drivers cited were rising cumulative trauma claim frequency, medical costs, and allocated loss adjustment expense.
On the Texas side, the Texas Department of Insurance accepted NCCI’s advisory loss cost filing with an overall average 3.8 percent decrease, effective July 1, 2026, under Commissioner’s Bulletin B-0001-26. For policies incepting on or after that date, carriers must use either their own filed relativities or the July 1, 2026 loss costs. They may not price off the 2025 or any earlier filing.
Now the important caveat, because this is where most coverage of rate news goes wrong. Both of these are advisory benchmarks, not premiums. A 6.6 percent advisory increase in California does not mean your bill rises 6.6 percent, and a 3.8 percent loss cost decrease in Texas does not mean your premium falls 3.8 percent. Insurers file their own rates against these benchmarks, and your own number then moves with your classification, your payroll, your experience modifier, and your carrier’s appetite for your trade. The direction is real and useful. The percentage is not a discount code.
What it does tell you is where to put your attention. A California contractor renewing on or after September 1 has good reason to check the renewal against the market rather than rolling it over unread, though whether any individual account moves up depends on its own carrier and rating. A Texas contractor renewing after July 1 has a reasonable basis for asking what the loss cost decrease did to their quote, and should not assume it was passed through.
California’s dual-wage thresholds change on September 1, and this one is worth checking
In brief: On September 1, 2026, the hourly wage thresholds on all 16 of California’s dual-wage construction classification families rise by $2 to $5 per hour. If your wages sit near a threshold and you do nothing, payroll can shift into a higher-rated classification and that part of your premium can rise without anything about your business having changed.
California splits several construction classifications into a high-wage and a low-wage version, because claim costs per unit of payroll differ between the two wage levels. Payroll for employees paid at or above the threshold may be assigned to the lower-rated high-wage classification, provided the recordkeeping requirements are met. Payroll for employees paid below it goes to the higher-rated low-wage classification. The recordkeeping condition matters: the high-wage assignment depends on being able to evidence the wages actually paid.
The Insurance Commissioner approved increases across all 16 dual-wage construction classification families, effective September 1, 2026, ranging from $2 to $5 per hour. Examples:
Carpentry (5403 and 5432) and steel framing (5632 and 5633): from $41 to $46 per hour.
Electrical work (5190 and 5140): from $36 to $40 per hour.
Here is why that matters more than it sounds. Suppose you run a carpentry crew paid $43 an hour. Under the old $41 threshold, that payroll sat in the high-wage classification. From September 1, with the threshold at $46, the same crew at the same wage falls below it, and that payroll moves into the higher-rated low-wage classification. Your people did not change and your safety record did not change, yet that payroll is now rated in the more expensive classification. Whether your total bill rises depends on the rest of the account, but that component of it goes up.
The action is simple and time-limited. Before any renewal dated September 1, 2026 or later, compare your actual hourly wages by classification against the new thresholds. Where a crew sits just under a threshold, it is worth running the arithmetic of a small wage increase against the classification change, because the answer sometimes favours the raise and sometimes does not. Confirm the thresholds for your own classifications with the WCIRB or with us before acting.
The experience modifier
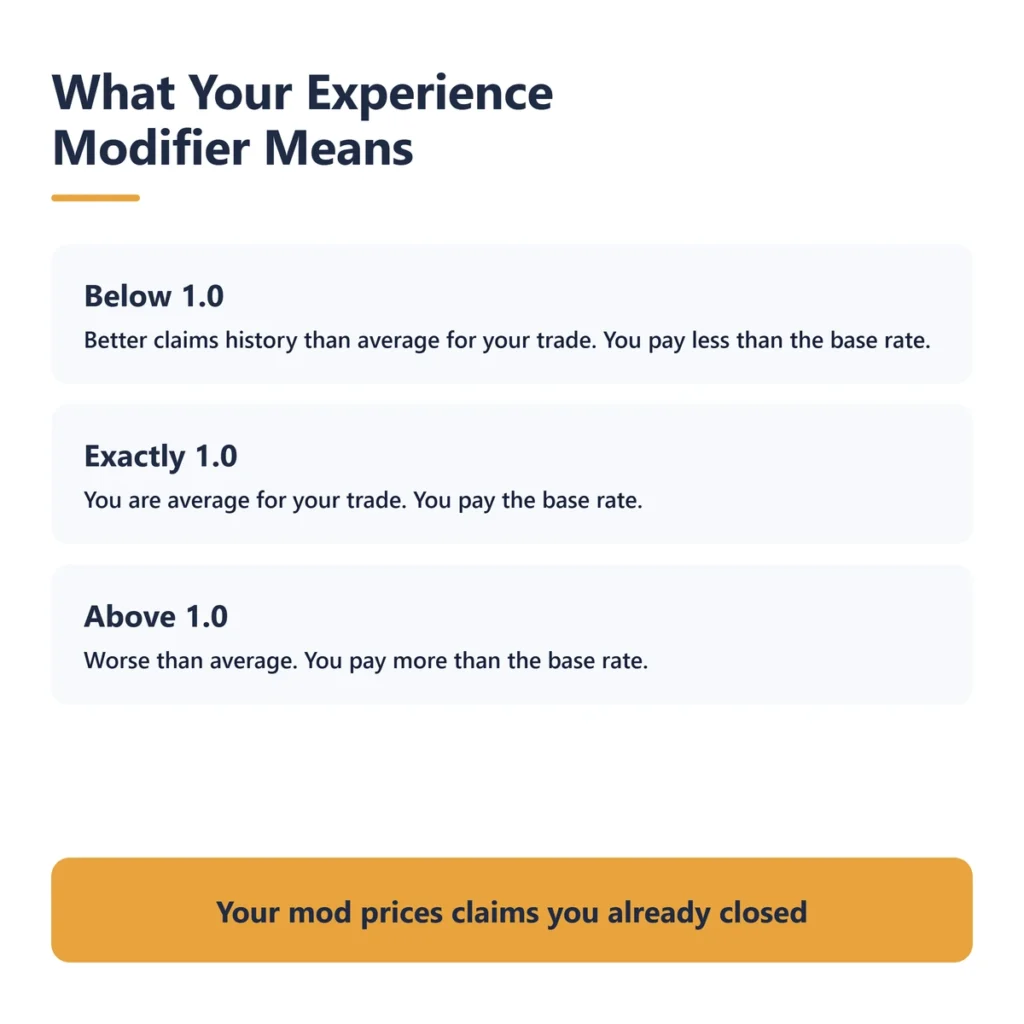
In brief: The modifier compares your claims history to the average for your trade. A 1.0 is exactly average, below 1.0 earns a credit, above 1.0 is a surcharge. You only receive one once your business is large enough to qualify.
A modifier of 1.0 means your loss experience matches what is expected for your classification and size. Below 1.0 means you have done better than expected and pay less than the base rate. Above 1.0 means worse, and you pay more. Because it multiplies the premium that is subject to experience rating, the effect compounds across your whole rated payroll rather than sitting on one line. Some charges, such as expense constants and terrorism charges, fall outside that multiplication.
You do not get a modifier automatically. In California the threshold is expressed in expected losses, calculated by multiplying payroll in each classification by that classification’s expected loss rate and summing the result. It is $10,800 for ratings effective through August 31, 2026, and rises to $11,700 for ratings effective on or after September 1, 2026. Note that the threshold is expressed in expected losses rather than in premium paid. In Texas, NCCI sets a subject-premium eligibility threshold that is reviewed periodically; below it, an employer is simply rated at 1.00. Ask your carrier where you sit rather than assuming.
Two things surprise contractors about the modifier. The first is that it is a lagging indicator. California builds it from a three-year window ending about one year and nine months before the rating effective date, and NCCI uses a comparable lag, so it prices claims from years you have already closed out and a good year takes time to show up. The second is that claim frequency is weighted more heavily than severity. Several small claims can therefore hurt your modifier more than one large one, which is why reporting hygiene and a genuine return-to-work programme matter more than they appear to.
Legitimate ways to pay less
In brief: Correct classification, subcontractor certificates, a real safety and return-to-work programme, and paying on actual payroll rather than an estimate. None of these are tricks, and all of them survive an audit.
Get the classification right. One of the costliest errors on a contractor’s policy, and the one most likely to have been wrong for years without anyone noticing. Have your split reviewed against the work your crews actually perform.
Collect a certificate from every subcontractor before they start, and check the dates. An uninsured sub’s payroll can be charged to your policy at audit. A certificate helps only if the coverage was actually in force for the period they worked, so a lapsed or mismatched policy will not save you. This is covered fully in our guide to workers comp for small construction businesses.
Run a documented safety programme. Fewer claims means a better modifier over time, and some carriers offer filed credits for formal safety programmes. Ask whether yours does.
Set up return-to-work. Bringing an injured worker back on light duty can shorten the period of wage-replacement benefits, which is often a large part of a claim’s cost.
Consider pay-as-you-go. Reporting actual payroll each period rather than paying against an annual estimate improves cash flow and helps limit the chance of a large year-end adjustment. The policy is still audited and the final audited premium is unchanged by how you paid it, so this reduces the surprise rather than the cost.
Ask about deductible options. Taking a deductible can lower premium where you have the balance sheet to absorb small claims, but it is only sensible if your frequency is genuinely low.
Shop the class, not just the carrier. Appetite for construction classifications varies widely between markets, and the same crew can be priced very differently by two carriers.
What to have ready for an accurate quote
Annual payroll split by classification, based on the work actually performed
Employee count, including any clerical staff
Subcontractor spend, and whether those subs carry their own coverage
Loss runs for the last three to five years
Your current experience modifier, if you have one
Whether owners or officers want to be included or excluded
The states you work in, and any certificate requirements written into your contracts
Frequently asked questions
How much does workers comp cost for contractors?
Published figures put construction workers compensation at about $175 per month, or $2,101 per year, across one large brokerage’s book of more than 40,000 construction customers, most of them with fewer than five employees. Those figures are medians of policies actually purchased. Within that group 44 percent pay under $150 per month and 69 percent under $300. For contrast, the same brokerage puts its all-industry small business average near $54 per month. The spread within construction is very wide because premium is driven by trade classification and payroll, so treat any average as orientation rather than a quote.
How is workers comp premium calculated?
Payroll divided by 100, multiplied by the rate for your trade classification, multiplied by your experience modifier. The base is payroll rather than revenue, which is why premium tracks the size of your crew instead of your turnover. The classification system and advisory values come from the WCIRB in California and from NCCI in Texas, though your insurer files the rate it actually charges. The experience modifier reflects your claims history against the average for your trade.
Why is workers comp so expensive for roofers?
Because rates are set by classification according to loss experience, and roof work carries fall exposure as a matter of course. Falls produce both frequent and severe claims, so roofing is consistently among the most expensive construction classifications, well above ground-level finishing trades. Fewer carriers actively compete for roofing, which tends to reduce pricing pressure. It is not always the single highest rated classification in a given state, and both the classification systems and the insurer multipliers differ between states.
Are workers comp rates going up in California in 2026?
The advisory pure premium rate rises 6.6 percent to an average of about $1.65 per $100 of payroll for policies incepting on or after September 1, 2026, following the Insurance Commissioner’s decision of July 10, 2026. The WCIRB had filed for 10.4 percent. Important caveat: this is an advisory benchmark that insurers file their own rates against, not a change to anyone’s bill, so a 6.6 percent advisory increase does not mean your premium rises 6.6 percent.
Are workers comp rates going down in Texas in 2026?
Advisory loss costs fell by an overall average of 3.8 percent effective July 1, 2026, under Texas Department of Insurance Commissioner’s Bulletin B-0001-26. Carriers must price off either their own filed relativities or the July 1, 2026 NCCI loss costs, and may not use earlier filings. As with California, this is an advisory benchmark rather than a premium change, so do not assume the decrease was passed through to your quote. It is worth asking.
What are the California dual-wage thresholds for construction?
California splits several construction classifications into high-wage and low-wage versions, and the hourly threshold rises on all 16 dual-wage classification families effective September 1, 2026, by $2 to $5 per hour. Carpentry (5403 and 5432) and steel framing (5632 and 5633) move from $41 to $46 per hour, and electrical work (5190 and 5140) moves from $36 to $40. Payroll at or above the threshold may be assigned to the lower-rated classification where the recordkeeping requirements are met, so if your wages sit just below a new threshold that payroll moves to the higher-rated one without anything else about your business changing
What is a good experience modifier?
Anything below 1.0 is better than average for your trade and earns a credit against the base rate. Exactly 1.0 is average. Above 1.0 is a surcharge, and because the modifier multiplies the premium subject to experience rating the effect compounds across your rated payroll. You only receive a modifier once your business is large enough to qualify. In California that test is on expected losses: $10,800 for ratings effective through August 31, 2026, rising to $11,700 for ratings effective on or after September 1, 2026. It is a lagging indicator, built from a three-year window ending about one year and nine months before the rating date.
How can I lower my workers comp premium?
Confirm your classifications match the work your crews actually perform, since misclassification can be an expensive error to leave in place. Collect a certificate of insurance from every subcontractor before they start and check that the coverage dates span the work, since without it you have nothing to produce at audit. Bear in mind the auditor also looks at whether the relationship is genuinely independent, so a certificate helps but does not decide it on its own. Run a documented safety programme and a return-to-work programme, since the rating formulas weight claim frequency more heavily than severity. Consider pay-as-you-go so instalments track actual payroll, which helps limit the chance of a large year-end adjustment, though the policy is still audited and the final premium is unchanged. And shop the classification rather than just the carrier.
Get an accurate workers comp price
An accurate number needs your payroll by classification, your loss history, and your subcontractor position. Send us those and we will price it properly against carriers with genuine appetite for your trade, in California and Texas. We are a licensed brokerage in both states, we shop multiple carriers rather than returning a single quote, and we issue the certificate once coverage is bound. See our overview of workers compensation for contractors, or start below.
This guide is general information for contractors in California and Texas, not legal, tax or individualised insurance advice. Advisory rate changes are benchmarks insurers file against and do not determine any individual premium.
Written and reviewed by Pascal Burke, Licensed Insurance Broker and founder of ContractorsInsured.net. Insurance brokerage services are provided by Pascal Burke Insurance Brokerage, Inc., licensed in California (#6015321) and Texas (#3305690).