If you have even one employee in California, you must carry workers compensation, and five licensed contractor classifications must carry it even with no employees at all. Texas is the opposite: coverage is generally optional for private employers, right up until a public project or the contract in front of you requires it. The trap that catches small builders in both states is subcontractors. Pay a sub who carries no coverage of their own and that payroll can land on your policy at your annual audit. ContractorsInsured.net is Pascal Burke Insurance Brokerage, Inc., licensed in California (#6015321) and Texas (#3305690). We place workers comp for small construction businesses in both states and issue the certificate once coverage is bound.
Do you need workers comp for a small construction business?
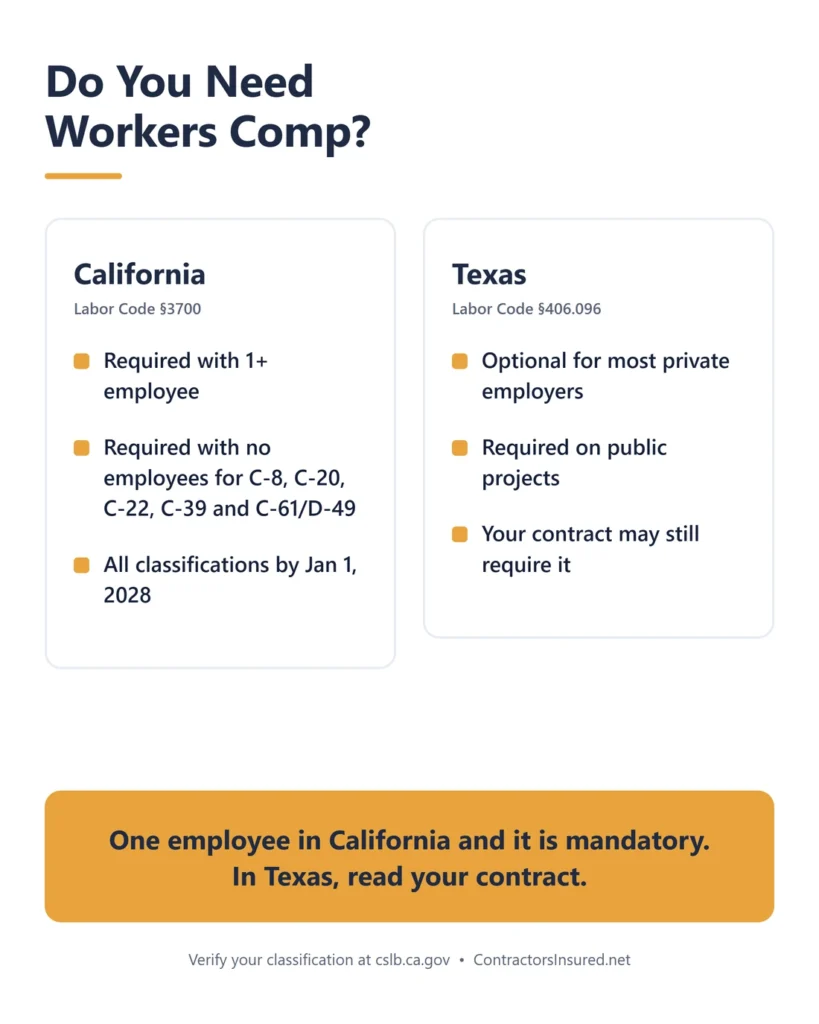
In brief: In California, yes, from your first employee, under Labor Code section 3700, and several contractor licence classifications must carry coverage even with no employees. In Texas, generally no, because the state leaves it optional for most private employers. In both states the contract you sign can settle the question regardless of what the state requires.
Most guidance on this subject answers for “small business” in general, which is not much use if you run a framing crew. Construction is treated differently from an office or a retail shop, because the work carries heavier injury exposure, the licensing boards get involved, and the general contractor above you has a direct financial interest in whether you are covered.
So the honest answer has three layers, and they apply in this order: what your state requires, what your licence requires, and what your contract requires. It is entirely normal for a Texas contractor to owe nothing to the state and still carry coverage on every job, because the general contractor will not let him on site otherwise
California: the licence classifications that must carry it with no employees
In brief: California requires workers compensation of every employer with at least one employee. On top of that, five licensed contractor classifications must carry coverage regardless of whether they employ anyone, and every remaining classification joins them on January 1, 2028.
Under California Labor Code section 3700, every California employer must secure workers compensation, and that obligation starts at a single employee. There is no small-employer grace band.
The contractor-specific rule is the part that surprises owner-operators. These classifications must carry coverage even with no employees:
- C-39 roofing, which has been in this position for years
- C-8 concrete
- C-20 warm-air heating, ventilating and air conditioning
- C-22 asbestos abatement
- C-61/D-49 tree service
The four joining roofing took effect on January 1, 2023. Every other licensed classification must carry coverage by January 1, 2028, a date set by Senate Bill 1455 (2024), which pushed back the earlier deadline in Senate Bill 216. If you have read that the universal requirement starts in 2026, that information is out of date.
Until then, a licensed contractor with no employees outside those classifications can still file an exemption with the CSLB. The document is the Exemption from Workers’ Compensation Insurance, form 13L-50, and it certifies under penalty of perjury that you have nobody employed in a manner subject to California workers compensation law. That route remains available in 2026. Verify your own position at cslb.ca.gov before relying on it, because filing that certificate while actually using labour is a serious problem.
Texas: optional by law, required by your contract
In brief: Texas does not require most private employers to carry workers compensation, which makes it the only state where going without is a legal choice. Two things override that: public works projects, and the subcontract you sign.
The first exception is the public project. Where a governmental entity enters into a building or construction contract, contractors and subcontractors must provide coverage for the employees working on that project under Texas Labor Code section 406.096, and a subcontractor has to give the general contractor certification of that coverage. Note the trigger: it is a governmental entity signing the contract, not merely government money somewhere in the funding.
The second is simply your own agreement. A private contract can require workers compensation where state law does not, so what you signed matters as much as what Texas requires. Read the insurance clause before you assume the state’s answer is the final one.
Opting out in Texas makes you a “non-subscriber,” which carries filing duties and strips away legal defences you would otherwise have if an employee sues. That is a bigger subject than this page, and we cover it properly in our guide to workers comp insurance in Texas.
What workers comp actually covers
In brief: Workers compensation pays for medical treatment of a work injury with no deductible or co-pay for the injured worker, replaces part of lost wages, and pays permanent disability and death benefits. The wage replacement percentages and weekly maximums differ between California and Texas.
- Medical treatment for the work injury, with no deductible or co-pay charged to the worker.
- Temporary disability, meaning wage replacement while the worker cannot work. California pays about two thirds, 66.67 percent, of average weekly wages, subject to a statutory maximum of roughly $1,764.11 per week for 2026. Texas pays 70 percent of the difference between the pre-injury average weekly wage and what the worker earns after the injury. A worker who was earning less than $10 an hour receives 75 percent for the first 26 weeks, after which the rate drops back to 70 percent. The maximum is roughly $1,271.00 per week for injuries in Texas fiscal year 2026, which runs October 1, 2025 through September 30, 2026. Both figures are adjusted annually, so verify the current numbers with the California Division of Workers’ Compensation and the Texas Department of Insurance. The Texas formula sits at Labor Code section 408.103.
- Permanent disability benefits where the injury leaves lasting impairment.
- Death benefits to dependants, plus burial costs.
For a small builder the practical value is simpler than the benefit schedule suggests. A serious fall becomes an insurance claim rather than a conversation about whether your business can absorb a six-figure medical bill.
What it does not cover
In brief: Workers compensation covers your employees, not your customers, your tools, or your truck. Within the policy itself, injuries outside the course of employment and a short list of excluded circumstances fall outside cover.
Commonly outside cover: injuries that did not arise out of and in the course of employment, injuries caused by intoxication, and intentional self-harm. Separately, workers comp does not touch third-party injury or property damage, which is what general liability is for, and it does not cover your equipment, which is inland marine.
One part of the policy is worth understanding because it is easy to overlook. Alongside the benefits section sits employers liability, which covers certain employment-related injury claims falling outside the ordinary benefit system, subject to its own conditions and exclusions. The classic construction example is a third-party-over claim, where an injured worker sues the general contractor and the general contractor turns around and sues you. It is the part that matters in the unusual cases, and it is one reason a bare-bones approach tends to be a false economy.
Owners, partners, and officers: who can leave themselves off the policy
In brief: Both states let certain owners exclude themselves, and the rules turn on your business structure and your ownership percentage. Excluding yourself removes your own coverage, and usually reduces the payroll your premium is calculated on, though minimum premiums and other rating factors mean the saving is not guaranteed. Either way it is a real trade-off rather than a free saving.
California. A sole proprietor is generally outside coverage but may elect to be included. A general partner or a managing member of an LLC may exclude themselves by signing a written waiver under penalty of perjury that the insurer accepts. A corporate officer or director can qualify to exclude themselves with at least 10 percent ownership, or with 1 percent where a specified relative owns at least 10 percent and the officer holds health insurance. A sole shareholder who is also the officer is automatically excluded unless coverage is elected. Limited partners, non-managing LLC members and officers who do not meet the ownership test cannot waive. The controlling rule is Labor Code section 3352.
Texas. Sole proprietors and partners are included unless they are named on the exclusion endorsement, WC 42 03 08. Corporate officers, and member-managers or managers of an LLC, may exclude themselves where they hold at least 25 percent ownership; below that threshold the insurer has to approve it. A working LLC member who is not a manager cannot exclude.
Think carefully before excluding yourself. Many group health plans coordinate with, or exclude, injuries covered by or eligible for workers compensation, so an owner-operator who opts out can find there is a gap for the exact accident most likely to happen to him. Whether that is true of your plan depends entirely on its wording, so read the coordination language, or ask us to, before deciding.
“The trap I see most often is an owner-operator excluding himself to trim the premium, then having an accident and finding his health plan treats a work injury as somebody else’s problem. Read the coordination language before you decide, not after.” Pascal Burke, Licensed Insurance Broker
No policy yet but a GC wants your certificate?
That is exactly what we do. We quote workers comp fast and issue the certificate right after binding
The uninsured subcontractor trap
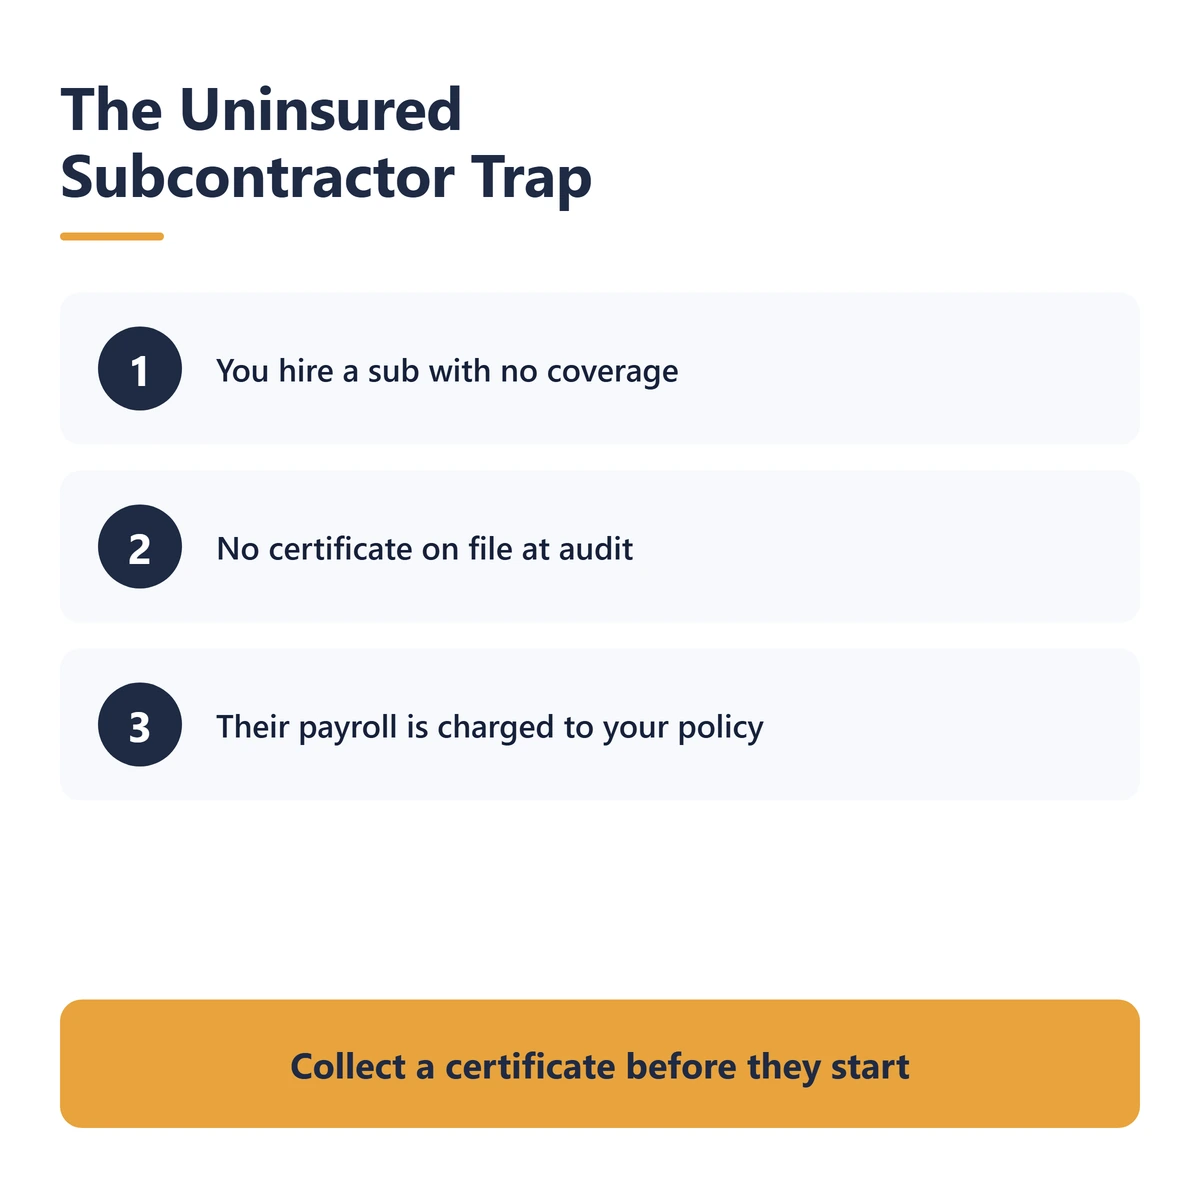
In brief: If you pay a subcontractor who carries no workers compensation of their own, that payroll can be charged to your policy at your annual premium audit. Calling the worker a 1099 does not settle it. A current certificate of insurance collected before the work starts is your best protection.
This is one of the most expensive surprises in small construction insurance, and it arrives months after the decision that caused it.
The mechanism is written into the policy. In California, the standard policy’s premium section allows premium to be charged for anyone whose work could create a workers compensation liability for you, and where payroll records are missing the insurer may use the contract price instead. In Texas, the applicable NCCI rule permits additional premium to be charged where satisfactory evidence of the subcontractor’s coverage is not produced.
What answers the charge is documentation rather than argument, though the carrier can still verify the underlying coverage and the working relationship:
- A valid workers compensation certificate of insurance from the subcontractor, covering the dates they actually worked for you.
- For a genuinely no-employee subcontractor, evidence of a valid contractor licence, any applicable exemption, and a real independent relationship.
- In Texas, a properly signed independent-relationship agreement on the applicable Division of Workers’ Compensation form can also be relevant, subject to verification.
The habit that heads most of this off takes about a minute per subcontractor: collect the certificate before they start, check that the dates cover your job, and keep it until after the audit. It is evidence the carrier can still verify rather than an automatic defence, but without it you have nothing to produce. See our guide to the certificate of insurance for what the document does and does not prove.
“A contractor uses a few uninsured helpers through a busy season, cannot produce a certificate for any of them at audit, and that payroll gets added to the policy after the fact. He budgeted one number and was billed another. The paperwork was the cheap part.” Pascal Burke, Licensed Insurance Broker
What happens if you do not carry it when you should
In brief: California treats failure to carry required workers compensation seriously. The state can issue a stop order that immediately prohibits your use of employee labour, assess penalties per employee, and in some circumstances pursue criminal charges. Separately, and new for 2026, the CSLB must impose minimum civil penalties starting at $10,000 and suspends the licence.
The specifics, all from the California Labor Code:
- A stop order prohibits the use of employee labour until you are covered, and can require you to pay affected employees for up to 10 days of lost time (section 3710.1). Disobeying it carries up to 60 days in county jail, a fine of up to $10,000, or both (section 3710.2).
- A penalty of $1,500 per employee applies when the stop order issues. For an uninsured period longer than a week, the penalty is the greater of twice the premium that should have been paid or $1,500 per employee employed during that period (section 3722).
- Where an injured worker brings a case, additional penalties of $2,000 per employee for a non-compensable claim or $10,000 per employee for a compensable one can apply, capped at $100,000.
- Operating without required coverage is a criminal offence under section 3700.5 where the person knew, or reasonably should have known, that coverage was required. It carries up to one year in county jail and a fine of at least $10,000, rising to a minimum of $50,000 for a repeat offence.
Separately from the Labor Code, the CSLB suspends the licence of a contractor who fails to maintain required coverage. Work performed during a suspension is unlicensed work, which puts your ability to enforce a contract and get paid at risk.
New for 2026: minimum CSLB civil penalties
Senate Bill 291 amended Business and Professions Code section 7125.4 effective January 1, 2026, adding minimum civil penalties for employing workers without coverage:
- A minimum of $10,000 per violation where the licensee is a sole owner.
- A minimum of $20,000 per violation for a partnership, corporation, LLC, or tribal business entity.
- Additional penalties for subsequent violations, up to $30,000 per occurrence.
The first two are minimums rather than ceilings. The third works the other way: $30,000 per occurrence is the cap on the additional penalties for subsequent violations. All of it sits on top of the Labor Code penalties above, and the licence is not renewed or reinstated until proof of coverage is filed. If you have been going without coverage on the assumption that the worst case is a fine you could absorb, that assumption changed on January 1.
None of that is intended as alarm. It is simply the honest downside of a decision some contractors make casually, and it is why we would rather quote the coverage than explain the penalties.
How coverage is bought, and roughly what it costs
In brief: Workers compensation is priced per $100 of payroll, by trade class code. Once a business is large enough to qualify, an experience modifier reflecting its claims history applies on top, along with other rating factors. Because payroll is the base, the number moves with your crew rather than with your revenue.
That is the short version, and the pricing mechanics deserve more room than this page can give them. For the full breakdown, including class codes, the experience modifier, and how construction trades compare, see our guide to contractor insurance costs, including workers comp class codes and the experience modifier.
What to have ready before you request a quote
- Payroll by class code, split by the work actually performed
- Employee count, including any clerical staff
- Subcontractor spend, and whether those subs carry their own coverage
- Claims history, and your experience modifier if you have one
- Whether owners or officers want to be included or excluded
- The states you work in
- The certificate and endorsement requirements written into your contracts
Frequently asked questions
Do I need workers comp for a small construction business?
In California, yes, from your first employee under Labor Code section 3700, with no small-employer exemption. Five contractor classifications must carry it even with no employees. In Texas coverage is generally optional for private employers, but public projects require it and general contractors commonly require it by contract before letting a subcontractor on site. In practice many small construction businesses in both states carry coverage regardless of which rule applies to them.
Do I need workers comp in California if I have no employees?
It depends on your licence classification. C-39 roofing, C-8 concrete, C-20 heating and air conditioning, C-22 asbestos abatement, and C-61/D-49 tree service must carry coverage regardless of employees. Other classifications can still file an exemption with the CSLB using form 13L-50, which certifies under penalty of perjury that you employ nobody subject to California workers compensation law. Every remaining classification must carry coverage by January 1, 2028 under Senate Bill 1455.
Is workers comp required in Texas?
Generally no. Texas is the only state where workers compensation is optional for most private employers. Two exceptions matter to contractors: a public project, meaning one where a governmental entity enters into the building or construction contract, requires coverage under Texas Labor Code section 406.096, and a private contract can require it even where state law does not. Opting out makes you a non-subscriber, which carries filing duties and removes important legal defences, covered in our dedicated Texas guide.
How fast can ContractorsInsured get a small construction business covered?
We move fast on workers comp and issue the certificate right after binding. ContractorsInsured.net is Pascal Burke Insurance Brokerage, Inc., licensed in California (#6015321) and Texas (#3305690), and we shop multiple carriers rather than returning a single quote, because appetite for construction class codes varies widely between markets. If a general contractor is holding up your start date over a certificate, tell us the requirement and we will tell you what is realistic.
What does workers comp actually pay an injured worker?
It pays for medical treatment of the work injury with no deductible or co-pay for the worker, plus wage replacement while they cannot work. California pays about two thirds of average weekly wages up to a 2026 maximum near $1,764.11 per week. Texas pays 70 percent of the difference between the pre-injury average weekly wage and post-injury earnings, and a worker who earned less than $10 an hour receives 75 percent for the first 26 weeks before it reverts to 70 percent, up to a maximum near $1,271.00 per week for injuries in Texas fiscal year 2026, which runs October 1, 2025 through September 30, 2026. Permanent disability and death benefits also apply.
Can I exclude myself as the owner?
Often yes, depending on structure and ownership. In California a general partner or managing LLC member can exclude themselves by signed waiver, and an officer or director generally needs at least 10 percent ownership. In Texas, sole proprietors and partners are excluded by endorsement, and officers or LLC managers holding at least 25 percent may exclude. Consider it carefully, because many health plans will not cover an injury that happened at work.
What happens if my subcontractor has no workers comp?
Their payroll can be charged to your policy at your annual premium audit, and where payroll records are missing the insurer may use the contract price instead. Calling the worker a 1099 subcontractor does not by itself prevent this. The protection is documentation: collect a current certificate of insurance from every subcontractor before they start work, confirm the dates cover your job, and keep it until after your audit close
What happens if I do not carry workers comp when I should?
in California the state can issue a stop order prohibiting your use of employee labour, with a penalty of $1,500 per employee, or for a longer uninsured period the greater of twice the unpaid premium or $1,500 per employee, plus additional penalties where an injured worker brings a case. Operating without required coverage is a criminal offence under Labor Code section 3700.5 where you knew or reasonably should have known it was required. Since January 1, 2026, Business and Professions Code section 7125.4 also carries minimum civil penalties of $10,000 for a sole owner and $20,000 for a partnership, corporation or LLC, and the CSLB suspends the licence.
Get workers comp for your construction business
If you are hiring your first employee, or a general contractor is asking for a certificate, we can price coverage properly against your payroll and class codes. We are a licensed brokerage in California and Texas, we shop multiple carriers for construction risks, and we issue the certificate once coverage is bound. See our overview of workers compensation for contractors, or get started below.
This guide is general information for contractors in California and Texas, not legal advice or a coverage determination. Whether any particular claim, exemption or penalty applies depends on your policy wording, your licence classification, the facts, and applicable state law.
Written and reviewed by Pascal Burke, Licensed Insurance Broker and founder of ContractorsInsured.net. Insurance brokerage services are provided by Pascal Burke Insurance Brokerage, Inc., licensed in California (#6015321) and Texas (#3305690).