Last updated: August 5, 2026
TL;DR: Concrete contractors pay a median-based average of about $119 per month for general liability, or $1,423 per year, according to Insureon’s concrete contractor policy data. Price moves with structural versus flatwork operations, payroll, vehicles, equipment values, claims, limits, and contract requirements. A $1 million per occurrence and $2 million aggregate policy is the common benchmark, but completed operations matters as much as the limit because cracking, settling, or spalling can appear after handoff. California regulates the trade through the C-8 license, while Texas has no state concrete license and relies more on city, permit, and contract rules. ContractorsInsured.net is a licensed brokerage in California and Texas (CA #6015321, TX #3305690): we quote concrete general liability the same business day and issue your COI right after binding.
| Concrete Contractor Insurance: 2026 Snapshot | ||
|---|---|---|
| Item | Figure | Detail |
| Insureon | $119 per month | GL |
| TechInsurance | $102 per month | GL |
| The Hartford | About $68 per month | Standalone GL |
| $1M/$2M standard limits | $1 million per occurrence | $2 million aggregate |
| Top concrete rate drivers | Heavy equipment values | |
| Top concrete rate drivers | Structural versus flatwork operations | |
| Top concrete rate drivers | Silica dust exposure | |
| Published figures are benchmarks, not quotes. | ||
What insurance does a concrete contractor actually need?
In brief:
Concrete contractors usually start with general liability and completed operations, then add equipment coverage, commercial auto, workers’ compensation, and umbrella coverage according to their crews, vehicles, contracts, and state rules, because a policy that handles a damaged driveway is not the policy that repairs a stolen power trowel or pays an injured employee.
Concrete combines third-party property damage, mobile equipment, vehicle movement, worker injury, and a long post-job defect exposure. That makes a one-policy answer unreliable. The right package depends on what you pour, how you move it, who works for you, and what the hiring contract requires.
General liability and completed operations
Contractor general liability insurance is the core policy for claims that your operations caused bodily injury or property damage to someone else. During a pour, that can mean wet concrete tracked into a finished lobby, damage to a garage door from a skid steer, or a visitor hurt near a chute. It also supplies a legal defense for covered lawsuits, subject to the policy’s terms and limits.
Products-completed operations coverage is especially important for concrete. A slab may look acceptable at handoff and later crack, settle, or spall. A foundation problem may damage framing, finishes, utilities, or other property after the crew is gone. Completed operations can respond when completed work causes covered bodily injury or property damage, but it does not turn GL into a warranty for the slab itself.
Keep the distinction clean: the resulting damage to other property may be covered, while the cost to tear out and re-pour your own defective work usually is not. Actual outcomes depend on the form, exclusions, endorsements, subcontractor exceptions, and facts of the loss.
Contractor’s equipment and inland marine
Mixers, pumps, power trowels, saws, compactors, screeds, forms, and smaller hand tools need property coverage that follows them away from a fixed shop. Contractor’s tools and equipment insurance, a form of inland marine coverage, can cover scheduled or blanket property in transit, at a jobsite, or stored off-site. Insureon’s concrete data puts the median-based average at $42 per month, or $505 per year.
The equipment schedule matters. A small walk-behind saw and a high-value pump are not the same underwriting problem. List ownership, values, storage, theft controls, and any borrowed or rented equipment accurately. Do not assume a pump truck scheduled by the ready-mix supplier becomes your insured equipment just because it appears on your job.
Commercial auto
Company-owned pickups, dump trucks, mixer trucks, and other road vehicles need commercial auto coverage. A personal auto policy may restrict or exclude business use, and GL does not replace auto liability for road accidents. Tell the insurer about trailers, radius of travel, driver records, vehicle weight, and whether employees use personal, hired, rented, or borrowed vehicles for work.
Workers’ compensation
Workers’ compensation addresses employee injuries and work-related illness, including medical benefits and lost wages as state law provides. Concrete crews face lifting, struck-by, burn, heat, and dust exposures. California and Texas handle the legal obligation very differently, which is why the state-specific section below matters.
Umbrella, professional, and pollution coverage
An umbrella or excess policy adds limits above scheduled liability policies when a GC, developer, public owner, or large project requires more protection. Professional liability can matter when the contractor supplies engineering, design, testing, mix specifications, or other professional advice. Pollution or environmental liability may also be needed where washout, slurry, fuel, or other pollutants create a jobsite exposure.
There is no nationwide rule that requires GL merely because the work is concrete. GCs, developers, owners, leases, city registrations, and bid contracts make it mandatory in practice for many jobs. California also imposes a separate liability insurance rule on LLC contractor licensees. A certificate of insurance proves policy details at a point in time, but it does not add coverage or endorsements by itself.
How much does concrete contractor insurance cost in 2026?
In brief:
At ContractorsInsured, we use $119 per month as a useful concrete GL planning benchmark because Insureon publishes that median-based average, but we quote the actual class, state, payroll, equipment, vehicles, and job mix because verified first-party figures range from about $68 to $119 per month before the contractor’s own underwriting details are applied.
These figures are not quotes and are not directly comparable samples. Each publisher uses its own customer book, eligibility rules, policy mix, and terminology. Still, the spread is useful because it shows why a contractor should compare the scope behind the number, not pick a provider from a search-result headline.
| Provider or marketplace | Verified concrete-specific public figure | What the page actually says |
|---|---|---|
| Insureon | $119 per month or $1,423 per year for GL | Median-based concrete customer data. Its sample policy has $1 million per occurrence and $2 million aggregate. Tools and equipment averages $42 per month or $505 per year. |
| NEXT | Quote required | The live concrete construction page publishes coverages and rate factors, but no concrete-specific premium. It names project type, location, payroll, and vehicle count and type as factors. |
| The Hartford | About $68 per month or $810 per year for standalone GL | Average for The Hartford small business customers who work with concrete. Its page also lists a concrete BOP average of about $141 per month or $1,687 per year. |
| biBERK | Quote required | The live construction page includes concrete construction companies in its appetite, but it does not publish a concrete-specific premium. |
| Thimble | Quote required | The current appetite guide lists Concrete Pouring and Concrete Work (No Foundation Work), but the public contractor page does not publish a concrete-specific price. |
| TechInsurance | $102 per month or $1,218 per year for GL | Median-based concrete customer data. Its sample policy has $1 million per occurrence and $2 million aggregate. |
Infographic snapshot copy: Insureon: $119 per month for GL. TechInsurance: $102 per month for GL. The Hartford: About $68 per month for standalone GL. The common shorthand is $1M/$2M standard limits, meaning $1 million per occurrence and $2 million aggregate. The three featured rate drivers are Heavy equipment values, Structural versus flatwork operations, and Silica dust exposure.
What changes a concrete contractor’s rate?
- Heavy equipment values. Pumps, ride-on trowels, saws, skid steers, forms, and other mobile property can raise the inland marine limit and may need individual scheduling.
- Structural versus flatwork operations. Sidewalk and decorative flatwork do not present the same completed-operations severity as structural slabs, foundations, elevated work, or load-bearing placements. Underwriters ask for the split.
- Mixer and pump truck exposure. Owned vehicles, hired units, trailers, delivery radius, driver records, and jobsite movement affect auto and liability pricing.
- Silica dust exposure. Cutting, grinding, drilling, and crushing concrete can create respirable crystalline silica. OSHA requires covered construction employers to control exposure, train workers, and maintain a written exposure control plan.
- Payroll and crew size. More field labor increases workers’ comp exposure, while revenue, subcontractor cost, and payroll can affect GL rating and audits.
- Public and commercial work. Larger owners and GCs may require higher limits, umbrella coverage, additional insured status, completed-operations wording, waiver of subrogation, or project-specific forms.
- Claims and continuity. Prior losses, cancellations, gaps, and a record of defect claims can change eligibility as well as price.
Marketplaces publish broad medians. We shop the contractor’s actual operations and class code, then compare carrier appetite in California or Texas. The cheapest number is not useful if foundations are excluded, owned equipment is missing, or the policy cannot supply the additional insured endorsement required by the contract.
California vs Texas: two opposite rulebooks for concrete contractors
In brief:
California classifies concrete work under the C-8 Concrete Contractor license and generally requires that license at $1,000 or more including labor and materials, while the exemption below $1,000 applies only when no permit is required and no workers are hired; Texas has no state concrete or general contractor license.
| Issue | California | Texas |
|---|---|---|
| State trade license | C-8 Concrete Contractor classification | No state concrete or general contractor license |
| Small-job rule | The exemption is only for an aggregate price below $1,000 including labor, materials, and all other items, with no required permit and no hired worker; other statutory conditions also apply. | No matching statewide concrete-license threshold; check the city, permit, project, and trade scope. |
| State GL rule | GL is not a blanket condition for every entity, but an LLC contractor license needs at least $1 million in liability insurance for five or fewer personnel of record. | Texas does not impose GL merely because the business pours concrete; city registration and contracts can require it. |
| State license bond | $25,000 contractor license bond; an LLC also needs a $100,000 employee or worker bond. | No state concrete-license bond because there is no state concrete license; project, city, or contract bonds can still apply. |
| Workers’ comp | Employers need coverage with one employee, and active C-8 licensees must carry coverage or valid self-insurance even without employees. | Most private employers may choose whether to subscribe, but non-subscriber duties and lawsuit consequences apply. |
California: C-8 licensing and insurance conditions
CSLB’s exact classification is C-8 Concrete Contractor. Its scope covers forming, pouring, placing, finishing, and installing specified mass, pavement, flat, and other concrete work, plus setting screeds for pavements or flatwork. The scope excludes businesses limited to plaster coatings or placing reinforcing steel.
The smaller exemption amount still circulating online is stale. AB 2622 changed Business and Professions Code section 7048 effective January 1, 2025. A license is generally needed when the aggregate project price is $1,000 or more including labor, materials, and all other items. Below $1,000 is not a free pass: the exemption requires no building permit and no employees, cannot be used to split a larger project, and has advertising conditions.
Every active California contractor license must maintain a $25,000 contractor license bond. An LLC licensee also needs a $100,000 employee or worker bond and liability insurance starting at $1 million for five or fewer personnel of record. The California contractor GL guide explains the insurance side, while the Los Angeles GL cost guide adds a local pricing lateral.
Texas: no state concrete license, but local and contract rules still matter
The current TDLR regulated-program list includes trades such as electrical and air conditioning, but not concrete or general contracting. Houston’s city business guide also states that there is no general contractor license at the city or state level, although permits are obtained job by job. This is a licensing fact, not an insurance waiver.
Local processes differ. Dallas’s current forms directory includes general contractor registration and a concrete, asphalt, and paving category. Houston routes building permits through its permitting center without a general contractor license. San Antonio says commercial GCs do not need city licensing or registration, but residential building and home-improvement categories have registration and liability-certificate rules.
A GC, developer, property manager, or owner can still require $1 million per occurrence and $2 million aggregate GL, additional insured status, completed-operations protection, and other endorsements by contract. Review the Texas contractor GL guide and the Houston GL cost guide for the matching state and metro context. Less state licensing does not mean less insurance in practice.
No policy yet but a GC or property manager wants a COI before the pour?
We quote concrete general liability the same business day, bind after you approve, and issue the COI right after binding. Workers’ comp and commercial auto move fast, but underwriting can take longer.
Workers' comp: California's C-8 condition vs the Texas opt-out
In brief:
California requires workers’ compensation when an employer has even one employee and separately makes coverage or valid self-insurance a condition of every active C-8 license, while Texas lets most private employers go without coverage but imposes non-subscriber notices, reporting duties, and serious litigation tradeoffs.
California C-8 holders cannot file the ordinary no-employee exemption
California employers must secure workers’ compensation with one or more employees. The live CSLB workers’ compensation page adds a trade-specific rule: all active C-8 Concrete contractors must carry a policy or valid Certification of Self-Insurance whether or not they have employees. CSLB’s 2022 bulletin states that this C-8 requirement took effect January 1, 2023.
The same live page says a C-8 holder cannot use the ordinary Exemption from Workers’ Compensation form. That is separate from the broader timetable for other contractor classifications. SB 1455 moved the previously announced all-licensee deadline, so contractors should rely on CSLB’s live page rather than a superseded date still repeated online.
For a solo C-8 holder with no employees, a zero-payroll workers’ compensation policy commonly called a ghost policy can be a practical option to discuss with a broker. It is not a substitute for employee coverage, and eligibility, owner exclusions, audits, minimum premiums, and CSLB filing must be confirmed for the actual entity and carrier.
Texas employers can opt out, but the choice removes protections
The Texas Department of Insurance says private employers can choose whether to carry workers’ compensation in most cases. An employer without coverage is a non-subscriber and must provide notices and make required state reports. If an employee sues for a work injury, Texas Labor Code section 406.033 removes defenses based on the employee’s contributory negligence, assumption of risk, or a fellow employee’s negligence.
Many GCs require workers’ compensation from subcontractors even when state law lets the employer opt out. Read the Texas non-subscriber workers’ comp guide before treating optional as consequence-free. A Texas contractor ghost policy guide explains a different compliance use case, but an owner-only setup does not provide employee benefits.
What concrete contractors actually get sued for
In brief:
Concrete claims most often start with third-party property damage, jobsite injury, vehicle movement, washout, or completed work that later damages something else, and the coverage answer changes by claimant and cause, so the same cracked slab can involve GL completed operations, a workmanship exclusion, professional liability, or no coverage.
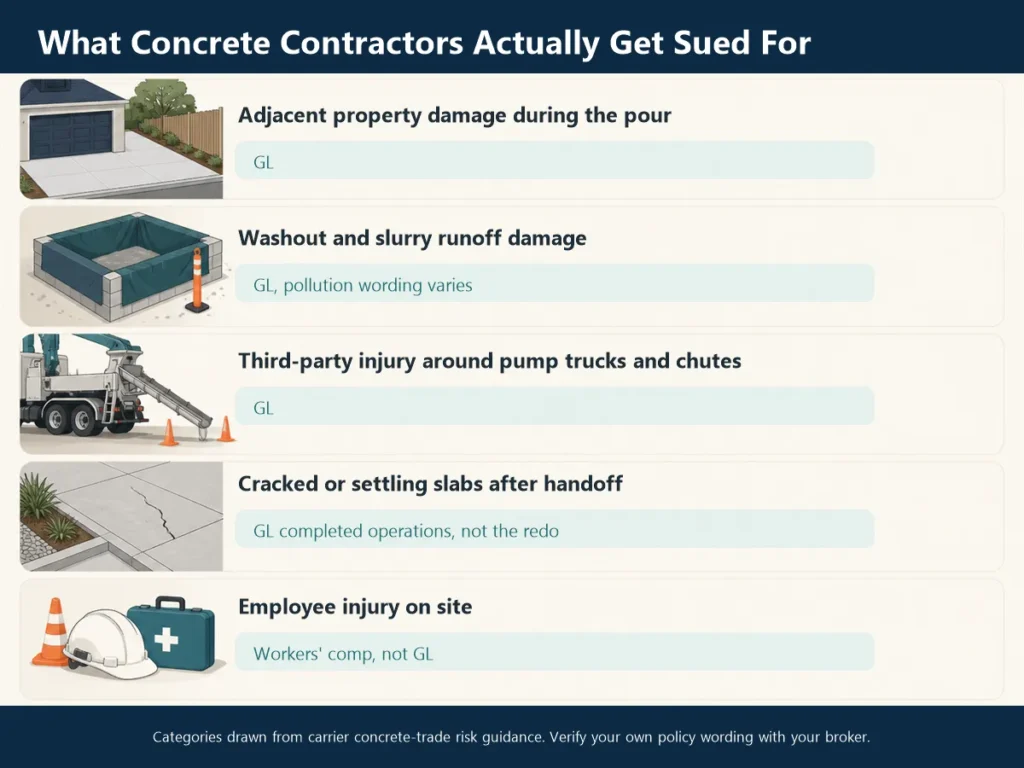
The following five categories are the body copy used in the claims infographic:
- Adjacent property damage during the pour | GL
- Washout and slurry runoff damage | GL, pollution wording varies
- Third-party injury around pump trucks and chutes | GL
- Cracked or settling slabs after handoff | GL completed operations, not the redo
- Employee injury on site | Workers’ comp, not GL
Categories drawn from carrier concrete-trade risk guidance. Verify your own policy wording with your broker.
Adjacent property damage during a pour or demolition
A skid steer can strike a garage door, demolition can crack adjoining hardscape, and wet concrete can stain finished surfaces or landscaping. This is the central third-party property-damage function of general liability coverage. The damaged property must belong to someone else, and care, custody, control or work-in-progress exclusions may affect a claim.
Concrete washout and slurry runoff
EPA construction guidance prohibits uncontrolled concrete washout discharge under its construction stormwater framework and explains that washwater can reach roads, storm drains, soil, and surface water. A GL claim may arise when runoff physically damages a client’s driveway, hardscape, landscaping, or other property, but pollution exclusions can change the result. Contractors pollution liability may be needed for cleanup and environmental exposure.
Vehicle and pedestrian injury around pump trucks and chutes
Ready-mix deliveries, reversing trucks, extended booms, hoses, and chutes put members of the public and other trades near moving equipment. GL can respond to third-party jobsite injury, while a road accident involving an owned truck belongs under commercial auto. Employee injury belongs under workers’ compensation, not GL.
Silica exposure from cutting and grinding
OSHA’s construction silica standard applies to occupational exposure from work such as cutting, grinding, drilling, or crushing concrete. This is primarily a worker-safety and workers’ compensation issue, not a reason to assume GL will pay. Dust that allegedly injures a visitor or damages third-party property requires a separate coverage analysis, including pollution wording.
Cracking, settling, spalling, and failed foundations after handoff
Completed-operations claims are the long tail. TechInsurance gives the concrete-specific example of a faulty foundation cracking and damaging a client’s home. The Hartford describes completed operations as covering eligible bodily injury or property damage caused after a service is finished. Neither source says GL pays to replace defective work with no resulting covered damage.
What concrete contractor GL does NOT cover
In brief:
Concrete contractor GL is built for covered third-party bodily injury and property damage, not every cost created by a bad job, so it usually does not pay to tear out and re-pour the insured’s own defective slab, replace owned equipment, cover employee injury, insure road vehicles, or guarantee design advice.
The faulty-workmanship line is the most important one to preserve. Most standard CGL policies have versions of the “your work” and incorrectly performed work exclusions. Insureon explains the practical split plainly: GL may cover damage caused by faulty work, but it does not pay to repair the contractor’s own faulty workmanship.
Example: If a defective pour cracks and damages the neighbor’s driveway or the client’s framing, covered resulting damage may trigger GL or completed operations. Breaking out and re-pouring your own slab is normally your business cost, warranty obligation, or contract dispute, not a GL benefit. Review actual policy wording because subcontractor exceptions and endorsements can matter.
| Loss | Policy to examine | Why GL is not the automatic answer |
|---|---|---|
| Tear-out and re-pour of your own defective slab | Contract, warranty, or specialty workmanship coverage | Faulty work and damage-to-your-work exclusions usually apply. |
| Employee injury | Workers’ compensation | GL excludes employee injury in the course of employment. |
| Crash in a company truck | Commercial auto | Road vehicle liability is handled by auto coverage. |
| Stolen mixer, saw, trowel, or forms | Contractor’s equipment or inland marine | Owned property is not third-party property damage. |
| Engineering or design error | Professional liability | Professional services and pure economic loss need separate analysis. |
| Pollution cleanup | Contractors pollution liability | GL pollution exclusions and exceptions vary by form. |
Start with the general liability coverage guide, then map every vehicle, worker, equipment item, professional service, and pollution exposure to the appropriate policy. Insurance is a contract, so a category name never overrides the wording, exclusions, endorsements, limits, and facts.
How to pay less for concrete contractor insurance
In brief:
Concrete contractors can lower avoidable premium by using the right class, reporting honest payroll and revenue, scheduling equipment accurately, comparing bundled and separate policies, choosing a deductible they can fund, paying annually when a real discount applies, and keeping COI and subcontractor records ready for audits.
- Class the work correctly. Flatwork, decorative concrete, foundations, elevated structural work, concrete pumping, and demolition can price differently. A broker should describe the actual mix rather than force every operation into the cheapest label.
- Use realistic revenue and payroll. Understating exposure can create a painful premium audit. Overstating it can make the deposit unnecessarily high. Update estimates when the book changes.
- Build an accurate equipment schedule. List high-value items, serial numbers, replacement values, storage, and theft controls. Use blanket limits only where the policy and item values support them.
- Compare a BOP with separate policies. Eligible small businesses may save by bundling GL and commercial property, but structural operations or heavy mobile equipment may require a different program.
- Compare annual pay and deductibles. Annual pay can remove installment charges or earn a carrier discount. A higher deductible can lower premium, but only choose one the business can pay after a loss.
- Keep COIs and subcontractor controls clean. Collect current certificates, written contracts, and required endorsements from subs. Missing proof can turn subcontractor cost into an audit charge.
- Send the bid packet early. Clean COI information helps avoid rush endorsements, duplicate policies, and a bind that cannot satisfy the contract. Contractors doing broader scopes can also review the general contractor insurance overview.
Frequently asked questions
In brief:
Concrete contractors most often ask about price, licensing, cracked slabs, neighbor damage, workers’ compensation, and COI speed, and the short answers depend on whether the loss involves the insured’s own work or other property and whether the contractor operates under California’s C-8 rules or Texas local requirements
How much is concrete contractor insurance?
Concrete contractor general liability averages about $119 per month, or $1,423 per year, in Insureon’s median-based concrete customer data. TechInsurance publishes $102 per month, while The Hartford reports about $68 per month for standalone GL among its concrete small business customers. Your quote can differ because structural work, payroll, revenue, vehicles, equipment, claims, state, limits, deductibles, subcontractors, and required endorsements all affect underwriting.
Do concrete contractors need a license in California?
Yes, California generally requires a C-8 Concrete Contractor license when the aggregate project price is $1,000 or more including labor, materials, and all other items. The exemption below $1,000 applies only when no building permit is required and no workers are hired, and it cannot be used to split a larger job. Licensed contractors must maintain a $25,000 contractor license bond, with additional rules for LLCs.
Do you need a license to do concrete work in Texas?
Texas does not issue a state concrete contractor or general contractor license. That does not remove local or project rules. Dallas uses contractor registration categories, Houston requires job-specific permits without a general contractor license, and San Antonio applies registration to certain residential and home-improvement work. A GC, city, developer, or owner can also require insurance, bonds, permits, additional insured status, and a COI by contract.
How fast can ContractorsInsured cover a concrete contractor?
ContractorsInsured can quote concrete general liability the same business day and issue the COI right after the policy is bound. Send the business name, state, concrete operations, revenue, payroll, subcontractor use, claims history, requested limits, effective date, and the GC’s insurance page in one complete request. Workers’ compensation and commercial auto move fast too, but carrier underwriting can require more time than a straightforward GL placement.
Does general liability cover a cracked concrete slab?
General liability may cover resulting third-party property damage caused by a cracked slab, but it usually does not pay to remove and replace the contractor’s own defective slab. For example, completed operations may respond if faulty foundation work later damages framing or finishes, subject to the policy. If the only loss is the slab itself and the cost to re-pour it, the faulty-workmanship or your-work exclusion usually controls.
Does concrete contractor insurance cover damage to a neighbor's property?
General liability can cover accidental damage that concrete operations cause to a neighbor’s property, subject to the policy’s exclusions, limits, and facts. Examples include a pour damaging an adjacent driveway, demolition cracking nearby hardscape, or equipment striking a garage door. Coverage can change if the property was in your care, custody, or control, if auto caused the loss, or if pollution wording applies to slurry runoff.
Do concrete contractors need workers' comp in California and Texas?
California employers need workers’ compensation with one employee, and every active C-8 Concrete licensee must carry coverage or valid self-insurance even without employees. Texas lets most private employers choose whether to subscribe, but a non-subscriber has notice and reporting duties and loses specified defenses in an employee injury lawsuit. Many GCs still require workers’ compensation from Texas subcontractors before they can enter the site.
How do I get a same-day COI as a concrete contractor?
We issue a concrete contractor’s COI right after general liability is bound, and we quote GL the same business day. For the fastest result, send the certificate holder’s legal name and address, job name and address, required limits, endorsement wording, bid deadline, and the full insurance-requirement page. Existing clients can request a COI; new contractors need active coverage before any certificate can be issued.
Get covered before your next pour
ContractorsInsured helps concrete contractors in California and Texas match general liability, completed operations, workers’ compensation, auto, equipment, umbrella, and COI requirements to the work they actually perform, with general liability quoted the same business day and the certificate issued right after binding.
Pascal Burke binds contractor policies in both states and understands why California C-8 compliance cannot be handled like a Texas bid packet. Send the concrete scope, payroll, vehicles, equipment, claims, current policy, desired date, and contract requirements so we can compare the right carrier class and issue usable documents.
Get a concrete contractor insurance quote
This article provides general educational information, not legal advice or a promise that a claim will be covered. Coverage, limits, exclusions, endorsements, availability, and pricing depend on the policy, carrier, underwriting, state, contract, and facts. Confirm current licensing and insurance obligations with the applicable agency and review coverage with your broker.
Written and reviewed by Pascal Burke, Licensed Insurance Broker. Pascal Burke is the founder of ContractorsInsured.net, a licensed insurance brokerage serving contractors in California and Texas. CA License #6015321. TX License #3305690.