TL;DR
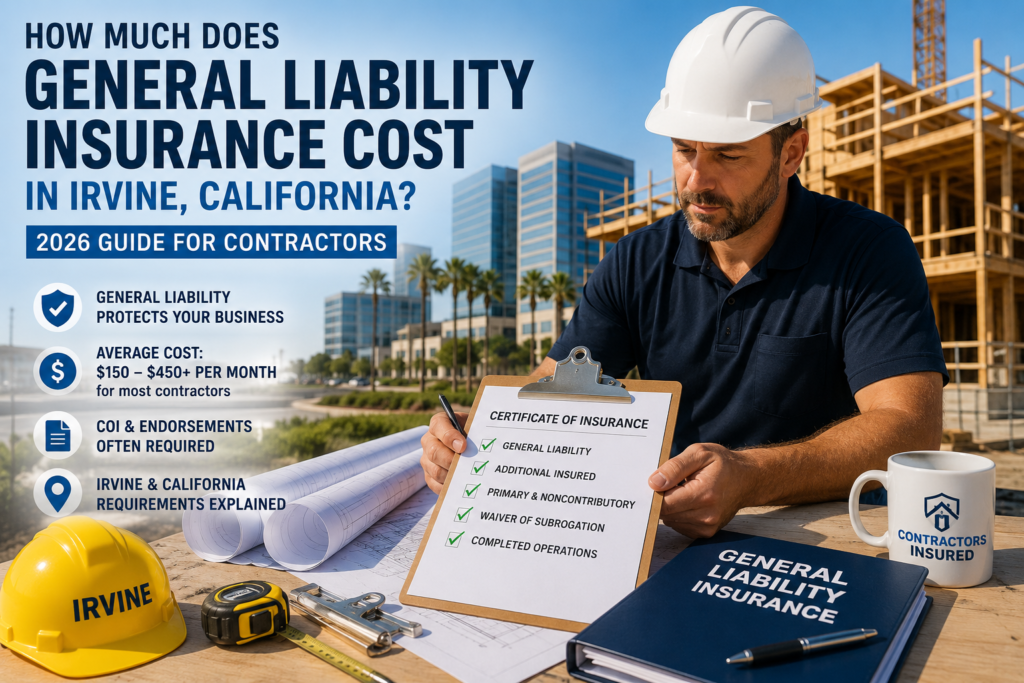
Irvine small businesses typically pay about $40 to $150 per month for general liability insurance, while contractors and higher hazard trades commonly pay about $150 to $450 or more per month, depending on trade classification, annual revenue, payroll, claims history, coverage limits, and required endorsements. Many Irvine general contractors, commercial property owners, and project owners require $1 million per occurrence and $2 million aggregate limits, along with Additional Insured status and a Certificate of Insurance (COI) before work begins, and public agency work often runs higher: the City of Irvine’s own purchase order terms require $2 million per occurrence and $4 million aggregate. As ContractorsInsured.net (CA #6015321, TX #3305690), we shop multiple California-admitted carriers for Irvine contractors, quote the same business day, and issue the COI right after binding.
What General Liability Insurance Covers (And What It Is)
In brief: General liability insurance protects contractors and businesses against third party claims involving bodily injury, property damage, personal and advertising injury, and completed operations. It is commonly required of Irvine contractors because many customers, landlords, municipalities, and general contractors ask for proof of coverage before work starts.
General liability insurance, commonly called Commercial General Liability (CGL) insurance, is a business insurance policy that protects an insured contractor or company against claims brought by third parties for accidental bodily injury, property damage, personal injury, and advertising injury arising from normal business operations.
Unlike workers’ compensation insurance, which protects employees, or commercial auto insurance, which covers company vehicles, general liability insurance focuses on claims made by people outside your business.
For Irvine contractors, this protection often becomes a contractual requirement before entering commercial developments, residential construction projects, tenant improvements, municipal work, or subcontract agreements throughout Orange County.
Typical coverage includes:
Third party bodily injury
Third party property damage
Products and completed operations
Personal and advertising injury
Legal defense costs for covered claims
Court judgments and settlements up to policy limits
For example, if a painter accidentally damages expensive flooring inside an Irvine office renovation, or a customer trips over a contractor’s equipment during a remodeling project, general liability insurance may respond to covered damages and legal expenses.
A standard ISO CG 00 01 general liability form commonly excludes or limits employee injuries, faulty workmanship itself, professional advice, company vehicles, and damage to your own tools and equipment. Those exposures generally need separate insurance policies, and what any individual policy covers depends on the form and the endorsements actually issued to you.
Contractors should also understand what general liability covers when comparing policies because coverage details, endorsements, exclusions, and carrier appetite vary significantly between insurers.
How Much Does General Liability Insurance Cost in Irvine in 2026?
In brief: Most Irvine contractors can expect general liability insurance premiums between approximately $150 and $450 or more per month, while many lower risk businesses pay around $40 to $150 monthly. At ContractorsInsured.net, we compare multiple California admitted carriers to find competitive pricing based on your actual trade classification rather than relying on a single insurer’s quote.
Most Irvine contractors pay between approximately $150 and $450+ per month for general liability insurance, depending on trade, payroll, annual revenue, claims history, required endorsements, and coverage limits.
That range reflects current California contractor pricing rather than the advertised “starting at” premiums often promoted by national online insurers.
Many advertisements quote very low monthly premiums because they target low risk office businesses, consultants, or home based operations. Construction businesses face substantially different underwriting because carriers evaluate:
Trade classification
Project size
Annual payroll
Gross revenue
Subcontractor usage
Claims history
Years in business
Requested policy limits
Required endorsements
Geographic service area
The result is a much wider premium range than many contractors expect.
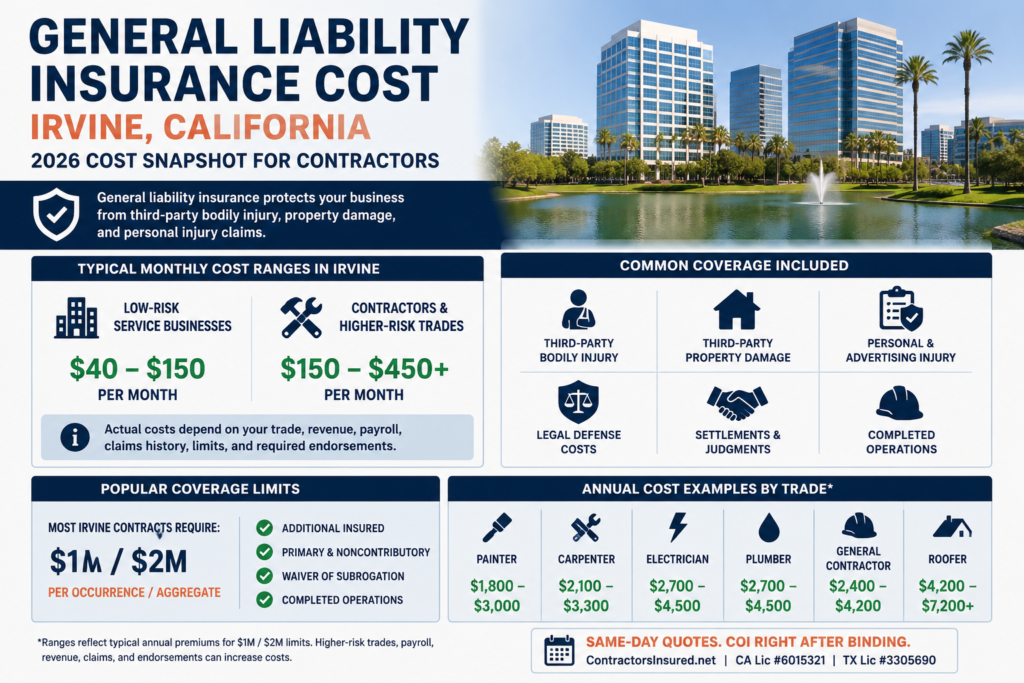
Typical Irvine Premium Ranges
Business Type | Typical Monthly Premium | Typical Annual Premium |
|---|---|---|
Low risk service businesses | $40 to $150 | $480 to $1,800 |
Small contractors | $150 to $300 | $1,800 to $3,600 |
Higher hazard contractors | $300 to $450+ | $3,600 to $5,400+ |
These figures should be viewed as planning ranges rather than guaranteed premiums because every carrier uses its own underwriting model.
National insurers publish broad benchmark pricing, but Irvine contractors often land above those averages due to California litigation costs, higher property values, larger commercial projects, and stricter contractual insurance requirements.
For perspective, this is what the widely quoted national benchmarks actually publish, and which population each one measures:
Insureon puts its California general contractor customers at about $144 per month, and construction businesses nationally at about $89 per month, or $1,069 a year, for general liability at $1 million per occurrence and $2 million aggregate with a $500 deductible. Those are medians of the policies its own customers bought, not averages, because Insureon excludes outlier high and low premiums.
MoneyGeek’s 2026 California report models a small business with one to four employees at $1 million and $2 million limits and puts the state average at $190 per month, with construction and contracting at $596 per month, or $7,148 a year. Those are modeled estimates rather than policies actually sold, and MoneyGeek rates California the most expensive state in the country for this coverage.
The Hartford publishes about $113 per month, or $1,351 a year, for construction businesses, and about $69 per month for $1 million of contractor general liability. Those are averages across its own customers.
NEXT, now trading as ERGO NEXT, advertises general liability from $19 per month and says that price point is most common in low risk industries, not in construction.
Those numbers disagree, and by a lot, because they measure different populations by different methods. Insureon and The Hartford report what their own customers bought, MoneyGeek models a standardized business, and none of the four is an Irvine figure. That is why the ranges above are planning ranges, and why a quote priced against your actual class code is the only number that settles it.
Pascal Burke, Licensed Insurance Broker
“One of the biggest mistakes we see is contractors comparing their premium to a national average without comparing trade classifications. Two Irvine contractors with similar revenue can have very different premiums simply because carriers classify their operations differently. We shop multiple California admitted carriers so clients can compare real options instead of accepting the first quote.”
Many Irvine contractors also need endorsements beyond standard liability coverage, including:
Additional Insured
Primary and Noncontributory wording
Waiver of Subrogation
Ongoing operations endorsements
Completed operations endorsements
Additional insured coverage is not one thing. It comes in an ongoing operations form (ISO CG 20 10) and a completed operations form (ISO CG 20 37), and many Irvine contracts want both. The City of Irvine goes further and will not accept an additional insured endorsement limited to ongoing operations at all.
These requirements can affect premium pricing, making it important to compare complete policy packages instead of focusing only on the monthly premium.
General Liability Insurance Cost by Contractor Trade in Irvine
In brief: Trade classification is one of the biggest pricing factors for general liability insurance. Contractors performing higher-risk work typically pay substantially more than businesses performing lower-risk services because carriers evaluate the likelihood and severity of future claims.
Insurance companies do not price every contractor the same. An electrician, roofer, and handyman may each generate similar annual revenue, but their exposure to injury, property damage, completed operations claims, and litigation differs significantly.
Below are planning ranges for Irvine contractors. Actual premiums vary by payroll, annual revenue, years in business, claims history, project size, subcontractor use, and required endorsements.
Trade | Typical Monthly Premium | Typical Annual Premium |
|---|---|---|
Handyman | $150 to $225 | $1,800 to $2,700 |
Painter | $150 to $250 | $1,800 to $3,000 |
Carpenter | $175 to $275 | $2,100 to $3,300 |
Landscaper | $175 to $300 | $2,100 to $3,600 |
General Contractor | $200 to $350 | $2,400 to $4,200 |
Electrician | $225 to $375 | $2,700 to $4,500 |
Plumber | $225 to $375 | $2,700 to $4,500 |
HVAC Contractor | $250 to $400 | $3,000 to $4,800 |
Concrete / Masonry | $275 to $450+ | $3,300 to $5,400+ |
Roofing Contractor | $350 to $600+ | $4,200 to $7,200+ |
These planning ranges reflect common California underwriting patterns. Your actual premium depends on the carrier’s appetite, your business profile, and your insurance requirements.
A contractor working exclusively on residential remodels will usually receive different pricing than one performing commercial tenant improvements, municipal work, or large mixed-use developments throughout Irvine and Orange County.
Why roofing and concrete contractors pay more
Roofers, concrete contractors, and masonry contractors typically generate higher premiums because claims involving falls, structural damage, water intrusion, or completed operations often produce significantly larger losses.
Conversely, lower-risk trades such as painting or handyman services generally produce fewer catastrophic liability claims, resulting in lower premiums when the rest of the underwriting profile is favorable.
Why General Liability Costs More (Or Less) in Irvine
In brief: Irvine contractors often pay more than national averages because insurance companies consider California claim costs, Orange County property values, local construction costs, contract requirements, and the size and complexity of projects performed throughout the region. At ContractorsInsured.net, we help contractors improve their underwriting profile before submitting applications to multiple carriers.
Several local factors influence pricing beyond your own company’s history.
1. Higher property values
Property damage claims in Irvine often involve expensive residential communities, commercial buildings, medical facilities, technology companies, and office developments.
Repairing damaged flooring, windows, cabinetry, HVAC systems, or electrical infrastructure costs significantly more than similar repairs in many other parts of the country.
Higher repair costs translate into higher insurance premiums.
2. Larger commercial projects
Many Irvine contractors work on:
Commercial office buildings
Healthcare facilities
Retail centers
Apartment developments
Industrial buildings
Technology campuses
Public infrastructure projects
Larger projects typically require higher policy limits and broader endorsements, increasing premium costs.
3. Strict contract insurance requirements
Many general contractors and project owners require subcontractors to carry:
$1 million per occurrence
$2 million aggregate
Additional Insured endorsement
Primary and Noncontributory wording
Waiver of Subrogation
Completed Operations coverage
Meeting these contractual requirements often increases premium costs compared with a basic liability policy.
4. California litigation environment
California generally experiences higher legal defense costs than many other states.
Because every general liability policy includes a legal defense obligation for covered claims, carriers price policies according to expected claim severity as well as claim frequency.
5. Payroll and subcontractors
Hiring additional employees or using subcontractors generally increases underwriting exposure.
Insurance companies evaluate:
Payroll
Number of employees
Subcontractor agreements
Certificates of Insurance collected from subcontractors
Quality control procedures
Better documentation often results in better underwriting outcomes.
6. Claims history
Contractors with several recent liability claims usually receive higher premiums.
Conversely, businesses with:
Clean loss history
Strong safety procedures
Stable operations
Several years in business
often qualify for more favorable pricing.
Pascal Burke, Licensed Insurance Broker
“Many contractors assume price is determined only by revenue. In reality, carriers evaluate the complete risk profile. We’ve helped Irvine contractors reduce premiums simply by correcting class codes, documenting subcontractor controls, and presenting cleaner underwriting information before approaching the market.”
No Policy Yet but a GC Wants a COI?
A general contractor asked for a Certificate of Insurance before work starts? That’s exactly what we help contractors with every day.
Button: Get GL Quoted and Bound Fast
Button: Request a COI
Cost by Coverage Limit
In brief: Higher policy limits provide additional financial protection but also increase premium costs. Many Irvine commercial contracts specify a minimum of $1 million per occurrence and $2 million aggregate, while larger projects, and City of Irvine work at $2 million per occurrence and $4 million aggregate, require higher limits or umbrella coverage.
The policy limit you choose directly affects your premium.
Although the difference between lower and higher limits is often smaller than contractors expect, selecting limits based only on price can become expensive if a contract requires additional coverage later.
Coverage Limits | Typical Use | Relative Cost |
|---|---|---|
$1M / $1M | Small projects where permitted | Lowest |
$1M / $2M | Most Irvine contractors | Standard |
$2M / $4M | Larger commercial projects | Higher |
Umbrella / Excess | Municipal and high-value contracts | Highest |
When do contractors need higher limits?
Higher limits are commonly required when working for:
Commercial developers
Property management companies
Municipal agencies
School districts
Healthcare facilities
Large retail centers
Industrial property owners
Rather than purchasing higher limits permanently, some contractors add umbrella or excess liability coverage only when contract requirements justify the additional premium.
Selecting appropriate limits should balance contractual obligations, business risk, and overall insurance costs rather than simply purchasing the cheapest available policy.
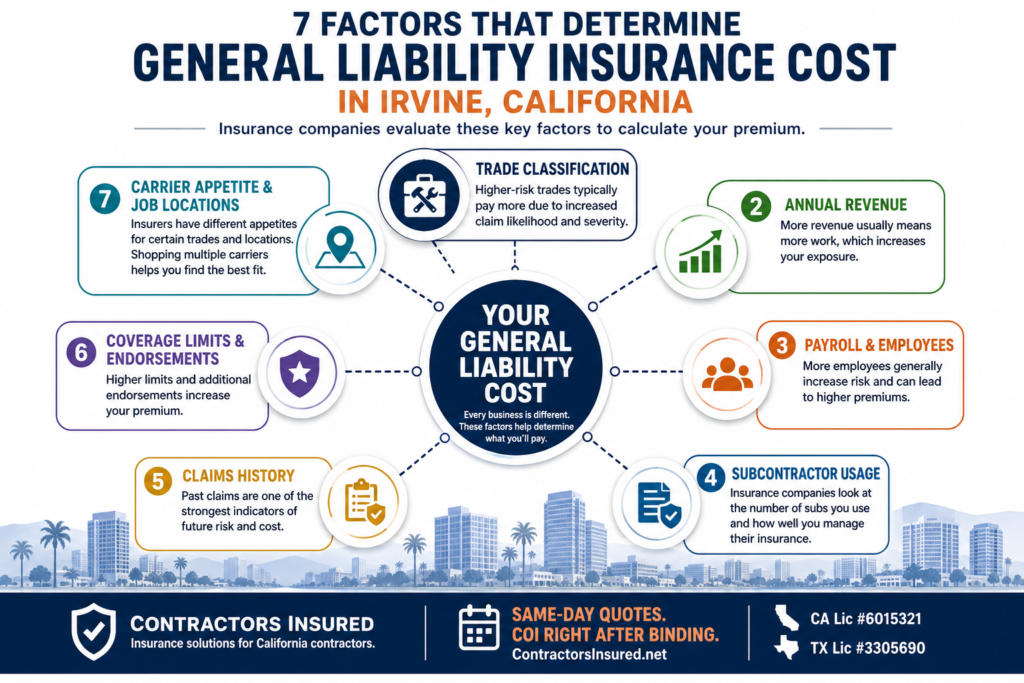
The 7 Factors Carriers Use to Price Your Policy
In brief: Insurance companies calculate general liability premiums by evaluating your business risk rather than using a flat price. Your trade classification, annual revenue, payroll, claims history, coverage limits, subcontractor use, and the types of projects you perform all influence what you’ll ultimately pay. At ContractorsInsured.net, we shop multiple California admitted carriers because each insurer weighs these factors differently.
No two contractors receive exactly the same premium because carriers evaluate several underwriting variables before issuing a quote.
Pricing Factor | Why It Matters | Potential Impact |
|---|---|---|
Trade Classification | Higher-risk trades generate larger claims | High |
Annual Revenue | More work generally creates greater exposure | High |
Payroll & Employees | Additional workers increase overall risk | High |
Subcontractor Usage | Poor documentation can increase underwriting concerns | Medium to High |
Claims History | Previous losses affect future pricing | High |
Coverage Limits & Endorsements | Higher limits and additional insured requirements increase premiums | Medium |
Carrier Appetite & Job Locations | Some insurers prefer certain trades and project types | Medium |
1. Trade Classification
Every contractor receives a classification code based on the work performed.
A roofing contractor, electrician, painter, and handyman may all report similar annual revenue, but their expected claim frequency and severity differ considerably.
Accurate classification is critical. A contractor assigned the wrong class code could pay significantly more than necessary.
2. Annual Revenue
Insurance companies generally expect businesses performing more work to have greater exposure to liability claims.
Revenue helps underwriters estimate how much work your company performs each year, although it is only one piece of the pricing equation.
3. Payroll and Employee Count
Companies with multiple employees typically present greater exposure than owner-only operations.
Underwriters evaluate:
Number of employees
Total payroll
Employee responsibilities
Field versus office staff
Supervisory structure
4. Subcontractor Usage
Many Irvine contractors rely on subcontractors.
Insurance companies often ask:
Do subcontractors carry their own insurance?
Do you collect Certificates of Insurance?
Are subcontractors required to name you as an Additional Insured?
Do written contracts exist?
Good subcontractor management often produces better underwriting results.
5. Claims History
Previous claims remain one of the strongest pricing indicators.
A contractor with several recent losses generally receives higher premiums than a similar contractor with a clean claims record.
6. Coverage Limits and Endorsements
Higher limits naturally cost more.
Additional endorsements such as:
Additional Insured
Primary and Noncontributory
Waiver of Subrogation
Completed Operations
may also affect pricing depending on the carrier.
7. Carrier Appetite and Project Location
Not every insurance company wants every type of contractor.
Some insurers specialize in:
Residential contractors
Commercial contractors
Artisan trades
General contractors
New businesses
Established businesses
Shopping multiple carriers often produces better pricing because underwriting appetites vary widely.
Irvine and California Insurance and Contract Requirements
In brief: California generally does not require every contractor to carry general liability insurance, but many Irvine contractors need it to win jobs, satisfy general contractors, comply with commercial lease requirements, or meet contract specifications. Certain California LLC contractors have additional insurance obligations under state licensing rules.
Understanding the difference between legal requirements and contract requirements is essential.
California contractor requirements
Licensed contractors in California must comply with Contractors State License Board (CSLB) regulations.
Important requirements include:
A $25,000 California contractor license bond.
LLC contractors must carry liability insurance under Business and Professions Code section 7071.19: total aggregate limits of at least $1 million for a company with five or fewer people on its personnel of record, plus another $100,000 for each additional person, up to a maximum of $5 million. If claims draw that aggregate down, the full limit has to be back in place by the start of the next policy period or the license is suspended by operation of law.
LLC contractors must also file the $100,000 LLC worker bond required by Business and Professions Code section 7071.6.5, which exists to protect workers if the company fails to pay wages, interest on wages, or fringe benefits.
Workers’ compensation insurance is required as soon as you hire employees, and active C-8 Concrete, C-20 Warm-Air Heating, Ventilating and Air-Conditioning, C-22 Asbestos Abatement, C-39 Roofing and C-61/D-49 Tree Service licensees must carry it whether or not they have employees, under Business and Professions Code section 7125. From January 1, 2028 that requirement extends to every license classification, and the only remaining exemption is a joint venture with no employees that files the statutory certification.
Although California generally does not require every licensed contractor to carry general liability insurance, the CSLB strongly recommends maintaining coverage because liability claims can create substantial financial exposure.
Irvine contract requirements
Many Irvine projects require contractors to provide:
General Liability Insurance
Certificate of Insurance (COI)
Additional Insured endorsement
Primary and Noncontributory wording
Waiver of Subrogation
Completed Operations coverage
Commercial landlords, developers, municipalities, property managers, and general contractors frequently require proof of insurance before allowing work to begin.
Working for the City of Irvine itself is a different standard. The City’s published purchase order terms and conditions require vendors performing onsite services to carry commercial general liability insurance at least as broad as the ISO occurrence form CG 00 01, including completed operations and contractual liability, with limits of not less than $2,000,000 per occurrence and $4,000,000 annual aggregate. The same terms call for automobile liability of not less than $1,000,000, workers’ compensation in accordance with the California Labor Code with a waiver of subrogation, and the City of Irvine and the Great Park Corporation named as additional insured by an actual policy endorsement, because a statement on a certificate is expressly not accepted. That additional insured endorsement may not be limited to ongoing operations. The City also asks for primary and non-contributory wording, carriers rated A.M. Best A- VII or better, a certificate at least five business days before work starts, thirty days of notice before coverage is cancelled, the same coverage from your subcontractors, and written City approval for any deductible or self-insured retention above $100,000. You can read the current terms on the City of Irvine purchasing page.
For contractors, this means that while general liability insurance may not always be legally mandated, it is often practically required to compete for commercial work.
What General Liability Insurance Does NOT Cover
In brief: General liability insurance protects against third-party liability claims, but it does not insure every business risk. Contractors typically need additional policies to fully protect their operations.
General liability insurance does not cover:
Professional mistakes
Design errors, engineering mistakes, consulting services, and professional advice generally require Professional Liability or Errors and Omissions insurance.
Employee injuries
Employee injuries are covered under Workers’ Compensation insurance rather than general liability.
Company vehicles
Vehicle accidents involving company-owned trucks, vans, or trailers require Commercial Auto insurance.
Tools and equipment
Contractor tools, equipment, and mobile property are typically insured under Inland Marine coverage.
Damage to your own work
General liability generally does not pay to replace defective workmanship itself.
Builders Risk insurance may also be needed during construction to protect materials and work in progress.
How to Lower Your General Liability Costs in Irvine
In brief: Contractors often reduce premiums by improving their underwriting profile rather than reducing coverage. Accurate business information, proper classification, fewer claims, and working with an independent broker frequently produce better long-term pricing.
Consider these practical strategies:
Use the correct class code
Incorrect classification is a common reason contractors overpay.
Bundle policies
Combining general liability with other business insurance may qualify for package discounts depending on the carrier.
Purchase appropriate limits
Buying limits that match your contracts avoids paying for unnecessary coverage while still meeting project requirements.
Improve claims management
A clean loss history helps maintain competitive premiums over time.
Pay annually
Some carriers offer discounts for annual premium payments instead of monthly installments.
Work with an independent broker
Every insurance company evaluates contractor risks differently.
At ContractorsInsured.net, we compare multiple California admitted carriers to help contractors find competitive pricing based on their actual operations instead of relying on a single insurer’s underwriting model.
What to Prepare Before Requesting a Quote
In brief: Providing complete information upfront allows insurers to produce more accurate quotes and reduces delays during underwriting. Contractors with organized business information often receive faster pricing and smoother policy issuance.
Before requesting a quote, gather:
California contractor license number
Legal business name
Entity type
Years in business
Annual revenue
Estimated payroll
Number of employees
Description of work performed
List of subcontractors used
Claims history
Current insurance information
Required coverage limits
Additional Insured requirements
Waiver of Subrogation requirements
Certificate of Insurance requirements
Project locations
Having this information ready allows us to approach multiple carriers immediately and identify the most competitive options for your business.
Get an Irvine General Liability Quote
Finding affordable contractor insurance is about much more than comparing monthly premiums.
The right policy should satisfy your contract requirements, provide appropriate coverage for your trade, and come from a financially strong insurer with experience serving California contractors.
At ContractorsInsured.net, we help Irvine contractors compare multiple California admitted carriers, explain coverage options clearly, and issue Certificates of Insurance immediately after coverage is bound. Our goal is to make the quoting process straightforward while helping contractors obtain coverage that meets both their budget and project requirements.
Whether you’re starting a new contracting business, renewing an existing policy, or bidding on a commercial project that requires additional endorsements, we’re ready to help.
Request your quote today and let our licensed brokerage compare multiple options for your business.
Frequently Asked Questions About General Liability Insurance Cost in Irvine, California
How much is general liability insurance in Irvine?
Most Irvine contractors can expect to pay between approximately $150 and $450 or more per month for general liability insurance, while many lower risk service businesses pay around $40 to $150 per month. Your actual premium depends on your trade classification, annual revenue, payroll, claims history, coverage limits, and any endorsements required by your contracts. The fastest way to determine your actual cost is to compare quotes from multiple California admitted insurance carriers.
How much is a $1,000,000 general liability policy for an Irvine contractor?
A $1 million per occurrence policy is the normal starting point rather than an upgrade, so most Irvine contractors buying one land inside the ranges above, roughly $150 to $450 or more per month depending on trade. Class code, payroll and revenue move that number far more than the limit does, which is why two contractors buying the same $1 million limit can be quoted very differently once a carrier looks at the business’s overall risk profile. Many Irvine contractors actually purchase $1 million per occurrence and $2 million aggregate limits because those limits are commonly required by general contractors, commercial property owners, municipalities, and project owners before work begins.
Is $200 a month a lot for general liability insurance?
Not necessarily. A $200 monthly premium may be very competitive for a California contractor depending on the trade and business operations. For example, a handyman with no employees might qualify for a lower premium, while an electrician, plumber, HVAC contractor, or general contractor could reasonably pay around that amount or more because of higher liability exposure. The premium should always be evaluated alongside the coverage limits, endorsements, and exclusions included in the policy.
How fast can ContractorsInsured cover an Irvine contractor?
At ContractorsInsured.net, we provide general liability quotes the same business day for most Irvine contractors after receiving complete business information. Once your policy is bound, we can issue your Certificate of Insurance (COI) immediately, which gives most contract holders the evidence of bound coverage they are asking for. A certificate is evidence rather than coverage, it does not amend the policy, and some contracts, the City of Irvine’s among them, also want the actual endorsements. If additional endorsements such as Additional Insured or Waiver of Subrogation are needed, we work with the carrier to obtain them as quickly as possible.
Do contractors in Irvine legally need general liability insurance?
California generally does not require every licensed contractor to carry general liability insurance. However, an LLC contractor must carry at least $1 million in total aggregate liability limits under Business and Professions Code section 7071.19, rising by $100,000 for each person on the personnel of record beyond five and capped at $5 million, and most commercial projects, general contractors, property managers and public agencies ask for proof of general liability coverage before work begins. Even when not legally required, maintaining general liability insurance is one of the most important ways contractors protect their business from potentially expensive third-party claims.
What insurance does Irvine require to register or contract?
It depends on who you are working for. For work performed for the City of Irvine itself, the City’s published purchase order terms require commercial general liability of at least $2 million per occurrence and $4 million annual aggregate on an ISO CG 00 01 occurrence form including completed operations, automobile liability of at least $1 million, workers’ compensation with a waiver of subrogation, and the City of Irvine and the Great Park Corporation named as additional insured by an actual endorsement rather than by a statement on a certificate. Private general contractors, landlords and developers in Irvine more commonly ask for $1 million per occurrence and $2 million aggregate plus a Certificate of Insurance, Additional Insured and Primary and Noncontributory wording. Read the limits written into your own contract before work begins, because those are the ones that control.
Does Irvine require registration or a business license for contractors?
Yes. The City of Irvine issues business licenses through its Community Development department, and its own application checklist asks contractors to upload a copy of their state contractor license. The City’s published fees are $76 for a business with fewer than ten employees and $152 to start with a $102 renewal at ten or more, each including the $4 State of California ADA fee, and a license runs twelve months from the first day of the month you apply. Apply within sixty days of your start date to avoid late fees. Vendors working for the City itself must hold a current Irvine business license before work begins, and a contractor based outside the city should confirm with the City licensing team whether a specific job triggers one. Your CSLB license must stay in good standing either way, and individual projects can carry their own permit requirements depending on location and scope.
How can I get a same-day Certificate of Insurance (COI) in Irvine?
If you already have an active policy, we can usually provide your Certificate of Insurance (COI) very quickly once we receive the certificate holder information and any required wording. If you do not yet have coverage, ContractorsInsured.net can provide a general liability quote the same business day in many cases, and after the policy is bound we issue the COI immediately so you can show evidence of coverage and keep your project moving forward, and we can go back to the carrier for any specific endorsements your contract names.
Author
Written and reviewed by Pascal Burke, Licensed Insurance Broker.
Pascal Burke is the founder of ContractorsInsured.net, a licensed insurance brokerage serving contractors in California and Texas.
California License #6015321
Texas License #3305690
Disclaimer
The information in this guide is intended for general educational purposes only and should not be considered legal, tax, or insurance advice. Premiums vary by carrier, trade classification, payroll, revenue, claims history, project type, coverage limits, endorsements, and underwriting guidelines. Always review your specific insurance requirements with a licensed insurance broker before purchasing coverage or signing a construction contract.
Irvine numbers sit inside a wider picture: see general liability insurance cost benchmarks.