Last updated: June 2026
Reviewed by: Pascal Burke, Licensed Insurance Broker, CA License #6015321, TX License #3305690
Quick Answer
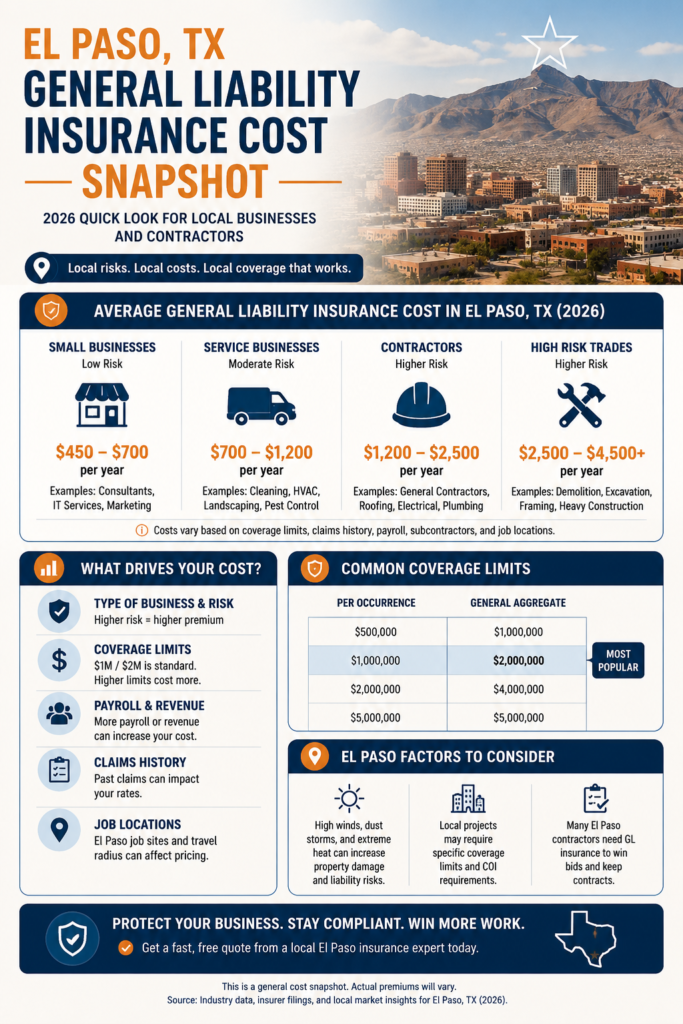
General liability insurance in El Paso, TX usually costs about $40 to $150 per month for lower-risk small businesses and about $150 to $400+ per month for many contractors in 2026. As ContractorsInsured.net (TX Lic #3305690), we shop multiple Texas-admitted carriers for El Paso contractors, quote the same business day, and issue the COI right after binding. A common baseline policy is $1 million per occurrence and $2 million aggregate. Final pricing depends on your trade, annual revenue, payroll, subcontractor use, prior claims, jobsite exposure, contract wording, and whether you need endorsements such as Additional Insured, Primary and Noncontributory, or Waiver of Subrogation. For most El Paso contractors, the cheapest policy is not always the right policy. A $1M/$2M general liability policy may satisfy many lease, bid, GC, vendor, and project-owner requirements, but some contracts ask for higher limits, umbrella coverage, commercial auto, workers’ comp, or specific COI wording.
- Small-business GL in El Paso: often $40 to $150 per month.
- Contractor GL in El Paso: often $150 to $400+ per month.
- Common limits: $1M per occurrence / $2M aggregate.
- Higher-risk trades: roofing, structural work, excavation, demolition, large GCs, and subcontractor-heavy operations.
- Common paperwork issue: the COI is not enough if the contract also requires endorsements.
- Fastest way to price correctly: send your trade, revenue, payroll, subcontractor details, claims history, and contract wording to a contractor-focused broker.
What general liability insurance covers
In brief: Commercial general liability insurance helps protect contractors against covered third-party bodily injury, property damage, and personal and advertising injury claims, plus legal defense costs. For El Paso contractors, premises and operations and completed operations coverage matter most.
General liability is often the first policy requested because it sits at the center of contractor risk. A GC, property owner, landlord, municipality, or vendor portal may ask for proof of coverage before you can start work, pull a permit, sign a lease, or get paid.
For contractors, general liability insurance for contractors may help with covered claims such as:
A visitor trips over materials near your work area and claims bodily injury.
A subcontractor’s operation damages a customer’s property and the claim is tendered back to your business.
A completed repair fails and causes property damage after the job is done.
A landlord, GC, or project owner asks for proof of liability limits before allowing work to begin.
A covered personal or advertising injury claim is made against your business.
The Texas Department of Insurance describes commercial general liability as coverage that protects business owners against liability claims for bodily injury, property damage, and personal and advertising injury. It also distinguishes premises and operations coverage from products and completed operations coverage, which matters for contractors because completed work can create claims after the crew leaves the job.
For the policy foundation behind the pricing in this guide, review our full contractor general liability coverage page.
What general liability does not cover
In brief: General liability is important, but it does not replace every contractor policy. It usually does not cover employee injuries, company vehicle accidents, damage to your own tools, professional design errors, most faulty workmanship costs, or every contract requirement.
A GL policy may be the first policy requested, but it is rarely the only policy a contractor needs.
General liability usually does not replace:
Workers’ compensation for employee injuries.
Commercial auto for vehicles used in the business.
Tools and equipment coverage for owned equipment, rented equipment, or inland marine exposure.
Professional liability or E&O for design, consulting, plans, specs, or professional advice.
Builder’s risk for property under construction.
Contractor bonds required by a city, owner, or licensing process.
Umbrella or excess liability when the contract requires higher limits.
None of the above decides a specific claim. What is covered or excluded on any given loss is determined by the policy actually issued, its endorsements and exclusions, who qualifies as an insured, and the facts of the claim. Treat this page as general information and read your own policy.
The practical point: a COI showing general liability can help you evidence coverage, but it does not automatically satisfy every contract clause. If the contract asks for Additional Insured, Primary and Noncontributory, Waiver of Subrogation, completed operations wording, or a specific edition of an endorsement, the broker needs to check whether the carrier can provide it.
How much does general liability insurance cost in El Paso, TX?
In brief: In 2026, many El Paso small businesses pay about $40 to $150 per month for general liability, while contractors commonly pay about $150 to $400+ per month for a standard $1M/$2M policy. Higher-risk trades, larger revenue, subcontractor-heavy operations, and prior claims can push premiums above that range.
Unlike Insureon’s broad national marketplace ranges for small-business general liability, ContractorsInsured.net works as a contractor-focused, multi-carrier broker, so the El Paso quote process can account for trade class, subcontractor exposure, required limits, COI wording, and carrier appetite before you bind coverage.
For statewide context on contractor pricing, limits, and COI requirements, see our guide to general liability insurance for Texas contractors.
Estimated 2026 El Paso GL cost by business type
Business type | Typical monthly range | Typical annual range | Notes |
Low-risk office or professional service | $40 to $75 | $480 to $900 | Lower premises and operations risk |
Small retail or local service business | $50 to $150 | $600 to $1,800 | Foot traffic, customer interaction, and property exposure affect price |
Handyman or small repair contractor | $100 to $250 | $1,200 to $3,000 | Scope, tools, subcontractors, and jobsite risk matter |
Plumbing contractor | $150 to $350+ | $1,800 to $4,200+ | Water damage and completed operations exposure can increase cost |
General contractor | $175 to $400+ | $2,100 to $4,800+ | Subcontractor use and project size drive underwriting |
Roofing contractor | $250 to $750+ | $3,000 to $9,000+ | Height exposure and completed operations often price harder |
Need an El Paso contractor GL quote? Get a contractor general liability quote and send your trade, revenue, payroll, subcontractor use, limits, and COI wording so we can match the request to carrier appetite.
Estimated GL cost by El Paso contractor trade
Contractor trade | Lower-risk profile | Higher-risk profile | Why pricing changes |
General contractor | $175 to $300 per month | $300 to $600+ per month | Subcontractor controls, project size, contract wording, and completed operations |
Roofing contractor | $250 to $500 per month | $500 to $1,000+ per month | Height exposure, hot work, torch work, claim severity, and carrier appetite |
Plumbing contractor | $150 to $300 per month | $300 to $600+ per month | Water damage, excavation, sewer work, and completed operations |
HVAC or mechanical contractor | $150 to $350 per month | $350 to $700+ per month | Equipment, refrigerants, installation risk, and state license requirements |
Concrete or masonry contractor | $150 to $350 per month | $350 to $700+ per month | Structural exposure, trip hazards, equipment, and site conditions |
Excavation or grading contractor | $250 to $600 per month | $600 to $1,250+ per month | Underground utilities, equipment, trenching, and public right-of-way work |
These are planning ranges, not guaranteed quotes. Carrier pricing depends on the exact application, class code, operations, revenue, payroll, subcontractor costs, job mix, and loss history.
Why El Paso contractors often pay more than generic small businesses
In brief: Contractors have higher premises, operations, and completed operations exposure than many office-based businesses. The risk is not just where you work today, but what happens after the job is complete.
A small consulting firm may have limited customer injury exposure and almost no completed operations exposure. A contractor is different. Crews work on active jobsites, use tools and equipment, enter customer property, hire subcontractors, and perform work that can create future property damage claims.
That is why broad small-business GL benchmarks can be misleading for construction. Insureon publishes a $45 per month figure for small businesses, but that is the median cost of policies sold to its own small-business customers across every industry, calculated to exclude outlier high and low premiums, not a national average and not a construction number. It is a useful general reference point; contractors often price above it because claim frequency and claim severity can be higher.
Key reasons El Paso contractor GL costs more:
Jobsites create third-party injury risk.
Work can damage customer property.
Completed operations claims may occur months after the job.
Subcontractors can create additional liability.
Contracts often require endorsements.
Roof, structural, excavation, utility, and mechanical work can have higher claim severity.
Prior claims can reduce carrier options.
Some carriers avoid certain trades altogether.
For the national coverage framework, start with our general liability insurance guide for contractors.
The 7 biggest cost factors for El Paso general liability insurance
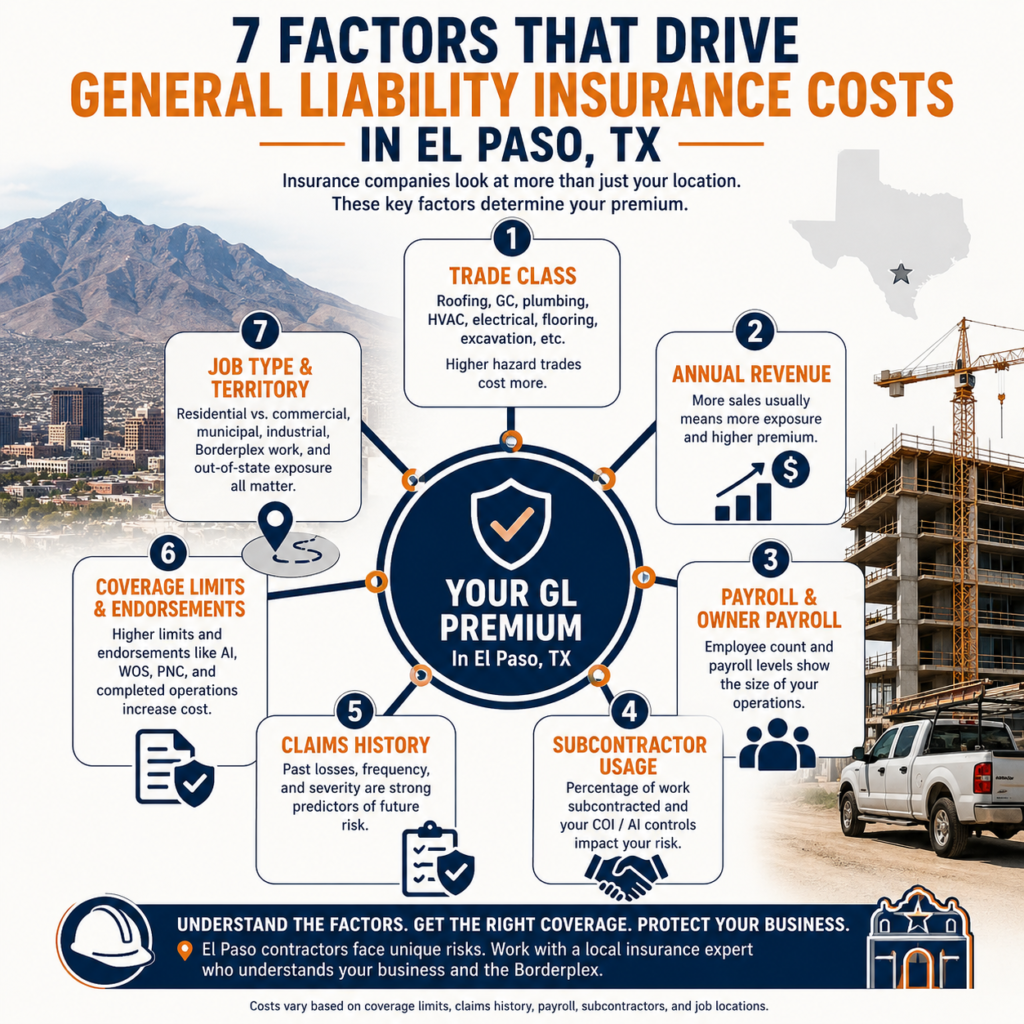
In brief: The biggest GL cost drivers are trade class, revenue, payroll, subcontractor use, claims history, coverage limits, and contract wording. The more clearly you explain your operations, the easier it is to avoid misclassification and quote delays.
Trade class
Trade is the first underwriting filter. A roofing contractor, plumbing contractor, general contractor, concrete contractor, and office consultant are not priced the same way.
High-risk trade factors include:
Work at heights.
Hot work.
Structural work.
Excavation.
Street, right-of-way, or utility exposure.
Sewer, drain, or water damage exposure.
Large subcontractor usage.
Multi-family or commercial projects.
Prior completed operations claims.
Revenue
Revenue helps carriers measure the size of your operation. Higher revenue usually means more work performed, more jobsites, more customers, and more potential claim exposure.
A solo contractor with $150,000 in annual revenue will usually price differently from a GC producing $2 million in annual revenue, even if both want the same $1M/$2M limits.
Payroll
Payroll helps underwriters understand how much labor you perform directly. It also helps separate employee exposure from subcontracted work.
For GL pricing, payroll can matter because it signals field activity. For workers’ comp pricing, payroll is even more central because workers’ comp is directly tied to class codes and payroll.
Subcontractor use
Subcontractors are one of the biggest reasons contractor GL quotes slow down.
A carrier may ask:
What percentage of your work is subcontracted?
Do you collect COIs from subs?
Do subs carry equal or higher limits?
Are you named Additional Insured on sub policies?
Do you use written subcontractor agreements?
Do subs provide Waiver of Subrogation if required?
Do you verify coverage before they start work?
If you are subcontractor-heavy and do not collect certificates, some carriers may decline or surcharge the account.
Claims history
Prior claims do not automatically make coverage impossible, but they matter.
A clean claim history can improve carrier appetite. Multiple claims, severe property damage, water damage, roofing claims, or repeated slip-and-fall losses can push pricing up or reduce options.
When explaining claims, be ready with:
Date of loss.
What happened.
Amount paid or reserved.
Whether the claim is open or closed.
What changed to prevent repeat losses.
Coverage limits
Most contracts start at $1M per occurrence and $2M aggregate. Some ask for $2M/$4M, a $5M umbrella, or project-specific aggregate wording.
Higher limits can increase cost, but the difference is not always dramatic. The bigger issue is whether your carrier can offer the exact contract requirements.
Endorsements and COI wording
A basic COI may not be enough. Many El Paso contractors need endorsement support, not just a certificate.
Common contract requests include:
Additional Insured.
Primary and Noncontributory.
Waiver of Subrogation.
Completed operations coverage.
Per-project aggregate.
30-day notice wording where available.
Specific certificate holder wording.
Project address or job number on the COI.
Texas contractors can also review our Texas contractor general liability guide for common $1M/$2M limits, Additional Insured wording, and COI workflow.
City of El Paso contractor registration and insurance notes
In brief: Some El Paso contractor registration categories involve city bonding and evidence of general liability insurance. City requirements are not the same as private contract requirements, so contractors should check both the city form and the actual contract.
The City of El Paso Contractor Registration Application states that general and pavement cut contractors are subject to fiduciary information requirements. Citing Title 18 of the El Paso City Code, the form references a building blanket construction bond of $50,000 for general contractors, a $10,000 bond for pavement cut contractors, and evidence of minimum general liability insurance of $100,000 with the City of El Paso listed as certificate holder.
That $100,000 is a headline figure, not the whole requirement. The city’s current Contractor Registration Requirements form (Rev. 07/2024) lists the $100,000 general liability certificate for the general contractor category and then attaches a note to it. The note states that the minimum limits of general liability coverage are $250,000 for bodily injury liability, including death, for each person and $500,000 in the aggregate, and $100,000 for property damage for each occurrence and $100,000 in the aggregate. A policy written only to a flat $100,000 is not what that note describes, so check the note against your certificate before you file it.
Engineering categories are held to more. On the same form the pavement cut, barricade and utility contractor categories carry higher general liability minimums than the general contractor category, in the $200,000 to $250,000 range rather than $100,000. If you cut pavement, set barricades or work in the public right of way, read your own category on the form rather than the general contractor line.
The bond has one substitution rule. The $50,000 blanket building construction bond is the general contractor default. A $10,000 bond can be submitted instead for a specific short list of work: irrigation installations, site lighting and landscape installations, temporary structure placement, mobile placement permits, temporary sign permits, tents over 200 square feet, fences, patch and paint permits, and pavement cuts or excavation in the public right of way. Confirm the category that applies to you with the One Stop Shop before you buy the bond.
That city registration threshold should not be confused with what a GC, owner, landlord, commercial customer, or vendor portal may require. Many private and commercial projects still ask for $1M/$2M limits, Additional Insured, Primary and Noncontributory, Waiver of Subrogation, commercial auto, workers’ comp, or umbrella coverage.
Practical takeaway:
Check the City of El Paso form if you are registering with the city.
Check the contract if you are working for a GC, owner, landlord, or commercial customer.
Check the permit packet if your job involves right-of-way, pavement cuts, excavation, or utility exposure.
Send the full insurance requirement page to your broker before buying coverage.
When Texas law requires general liability, not just the contract
City registration is only one layer. Three Texas trade licences carry a general liability requirement as a condition of holding the licence, and each one covers a trade priced in the tables above. El Paso’s own requirements form registers electrical, mechanical and plumbing contractors off these same state licences.
Electrical, electrical sign and residential appliance installation contractors must carry at least $300,000 per occurrence, $600,000 aggregate, and $300,000 aggregate for products and completed operations (16 TAC 73.40).
Air conditioning and refrigeration contractors must carry at least $300,000 per occurrence, $600,000 aggregate and $300,000 products and completed operations on a Class A licence, or $100,000, $200,000 and $100,000 on a Class B licence (16 TAC 75.40).
Responsible master plumbers must file a certificate of insurance with the state board before working as an RMP, for commercial general liability of not less than $300,000 for all claims arising in a one-year period (Tex. Occ. Code 1301.3576 and 1301.552).
These are licence conditions, so they apply whether or not a customer asks for a certificate. Confirm your own trade’s current requirement with the licensing agency before you rely on it.
Certificate of Insurance requirements in El Paso
In brief: A Certificate of Insurance is informational evidence that the listed policies were in force on the date it was issued. It is not the policy itself, it does not confer coverage, and it does not automatically change your policy. If the contract requires special status for a GC, owner, landlord, or city, an endorsement may be needed.
A COI usually shows:
Named insured.
Insurance carrier.
Policy number.
Effective dates.
General liability limits.
Other policies such as auto or workers’ comp, if applicable.
Certificate holder.
Description of operations.
Producer or agency.
The certificate holder may be:
A GC.
A property owner.
A landlord.
A city department.
A vendor portal.
A project owner.
A lender.
A property manager.
Already insured through ContractorsInsured.net and just need proof for a job? Request a COI with the certificate holder name, project address, required limits, and any Additional Insured, Primary and Noncontributory, or Waiver of Subrogation wording.
Important warning: Do not assume that a line typed into the COI description box creates coverage. If the requirement says “must be named Additional Insured by endorsement,” the policy needs endorsement support from the carrier.
El Paso GL cost examples
In brief: A $1M/$2M general liability policy can price very differently depending on the trade, revenue, payroll, subcontractor use, and contract wording. Below are planning examples, not guaranteed quotes.
Example 1: Small handyman or repair contractor
Profile:
El Paso sole owner.
Light residential repair work.
No employees.
Limited subcontractor use.
$120,000 annual revenue.
No claims.
Needs $1M/$2M GL and basic COI.
Likely planning range: $100 to $225 per month.
Why: The trade risk is moderate, the revenue is limited, and the account is clean. Pricing could increase if the contractor performs roof work, structural work, plumbing, electrical, or excavation.
Example 2: Plumbing contractor
Profile:
Small plumbing business.
Two employees.
$450,000 annual revenue.
Mix of residential and light commercial.
Occasional subcontractor use.
No major claims.
Needs Additional Insured for a commercial job.
Likely planning range: $175 to $400 per month.
Why: Water damage and completed operations exposure matter. Contracts may also ask for commercial auto and workers’ comp.
Example 3: General contractor
Profile:
El Paso GC.
$1.2 million annual revenue.
Subcontracts 60 percent of work.
Performs remodels and small commercial projects.
Needs $1M/$2M GL, Additional Insured, Primary and Noncontributory, and Waiver of Subrogation.
Likely planning range: $300 to $750+ per month.
Why: Subcontractor controls are central. Underwriters will want to know whether the GC collects COIs, requires equal limits, uses written agreements, and tracks certificates.
Example 4: Roofing contractor
Profile:
Roofing contractor.
$900,000 annual revenue.
Crews work at heights.
Commercial and residential roofing.
Prior small property damage claim.
Needs $1M/$2M GL and multiple project COIs.
Likely planning range: $500 to $1,250+ per month.
Why: Roofing is one of the harder contractor classes. Height exposure, completed operations, weather-related claims, and prior loss history can limit market options.
How El Paso compares with other Texas metros
In brief: El Paso can be somewhat more affordable than larger, denser Texas metros for some business classes, but contractor GL pricing still depends more on trade and operations than city name alone.
For nearby Texas metro comparisons, see our San Antonio general liability insurance cost guide and our Dallas general liability insurance cost guide.
Local pricing can shift by:
Competition among carriers.
Local construction volume.
Claim patterns.
Trade concentration.
Commercial property values.
Labor availability.
Litigation patterns.
Subcontractor practices.
Type of work performed.
A low-risk business in El Paso may still pay less than a roofing contractor in El Paso. A clean plumbing contractor in El Paso may pay less than a subcontractor-heavy GC in any Texas metro. That is why trade and operations matter more than the city alone.
Why OSHA and jobsite safety matter to GL pricing
In brief: OSHA does not set your general liability premium, but safety practices can affect underwriting. Contractors with better controls, training, documentation, and subcontractor management often present a cleaner risk.
OSHA describes construction as a high-hazard industry involving activities such as construction, alteration, and repair. Construction workers may face hazards such as falls, machinery, heavy equipment, electrocution, silica dust, and asbestos.
For GL underwriting, safety culture can matter because it signals how the contractor manages risk.
Useful underwriting positives include:
Written safety program.
Fall protection procedures.
Trenching and excavation controls.
Hot work controls.
Jobsite inspection logs.
Subcontractor safety requirements.
Written contracts with subs.
COI tracking for subs.
Incident response procedures.
Clean claims history.
This does not mean every carrier gives a direct discount for every safety measure. It means better documentation can help a broker tell a cleaner underwriting story.
How to lower your general liability insurance cost in El Paso
In brief: You may not be able to make a high-risk trade cheap, but you can often improve quote quality by reducing uncertainty. Clean applications, accurate classifications, subcontractor controls, and complete contract wording can help.
Here are practical ways to improve your quote:
Describe your work accurately
Do not call yourself a handyman if you perform roofing, plumbing, excavation, structural work, or commercial GC work. Misclassification can create quote problems, audit issues, and claim disputes.
Separate revenue by operation
If you do multiple types of work, break out revenue by category.
Example:
50 percent residential remodels.
20 percent light commercial tenant improvement.
15 percent plumbing repair.
10 percent subcontracted electrical.
5 percent other.
This is better than saying “general construction.”
Track subcontractor COIs
If you use subs, collect certificates before work begins. Require equal or higher limits when possible. Keep records.
Use written subcontractor agreements
A written subcontractor agreement can help clarify scope, insurance requirements, indemnity obligations, and certificate expectations. Ask legal counsel about contract language.
Send the insurance requirement page before binding
Do not buy a policy first and then discover it cannot provide the endorsement the GC requires.
Keep claims documentation organized
If you had a prior claim, explain what happened and what changed. A vague loss history is harder to underwrite than a clear one.
Avoid buying on price alone
Cheap coverage is not helpful if it excludes your actual work, cannot issue the required COI, or creates problems when a job starts.
What to send for an accurate El Paso GL quote
In brief: The more complete your information, the faster a broker can route your account to the right carrier.
Send:
Legal business name.
DBA, if applicable.
Entity type.
Business address.
Years in business.
Owner experience.
Trade or trades performed.
Residential vs commercial percentage.
New construction vs remodel vs repair percentage.
Annual revenue.
Payroll.
Subcontractor cost.
Number of employees.
Claims history for the last 3 to 5 years.
Current policy declarations, if available.
Contract insurance requirements.
Needed limits.
Certificate holder information.
Endorsement requests.
Job address or project name.
Bid deadline or compliance deadline.
If you need general liability insurance for an El Paso bid, lease, GC requirement, vendor portal, or jobsite COI, start a contractor insurance quote.
Common mistakes El Paso contractors make when buying GL
In brief: Most problems come from buying the cheapest policy without checking trade classification, exclusions, subcontractor rules, completed operations, or endorsement availability.
Mistake 1: Buying a policy before checking the contract
A policy may be active but still fail a vendor portal. Send the contract first.
Mistake 2: Assuming every COI request is simple
Some COI requests are simple. Others require endorsements. The difference matters.
Mistake 3: Ignoring subcontractor controls
Subcontractors can affect pricing, eligibility, audits, and claims. Keep clean records.
Mistake 4: Choosing the wrong trade class
If the application understates your work, the quote may look cheaper but create trouble later.
Mistake 5: Forgetting completed operations
Contractors need to care about claims after work is done, not just accidents during the job.
Mistake 6: Waiting until the day before mobilization
Rush requests create errors. Start early when possible.
Mistake 7: Not asking whether endorsements are available
Carrier appetite varies. A broker should confirm endorsement availability before you rely on the policy for a contract.
FAQs
How much is general liability insurance in El Paso, TX?
General liability insurance in El Paso often costs about $40 to $150 per month for lower-risk small businesses and about $150 to $400+ per month for many contractors in 2026. Higher-risk contractors, roofers, excavation contractors, subcontractor-heavy GCs, and businesses with prior claims may pay more.
What limits do El Paso contractors usually need?
Many contracts start with $1 million per occurrence and $2 million aggregate. Some contracts require higher limits, umbrella coverage, Additional Insured, Primary and Noncontributory, Waiver of Subrogation, or completed operations wording.
Is general liability required by Texas law for all contractors?
There is no single statewide general liability rule covering every Texas contractor, but there are real exceptions. Electrical, electrical sign and residential appliance installation contractors (16 TAC 73.40), air conditioning and refrigeration contractors (16 TAC 75.40) and responsible master plumbers (Tex. Occ. Code 1301.3576 and 1301.552) must carry general liability as a condition of the state licence. Beyond those, requirements come from city registration, contracts, leases, GCs, owners, vendor portals or project-specific rules. Always check your exact trade, city, and contract.
Does the City of El Paso require general liability insurance?
The City of El Paso Contractor Registration Application references minimum general liability evidence of $100,000 for contractors required to be bonded, with the City of El Paso listed as certificate holder. For pavement cuts or excavation in the public right of way, the city’s Contractor Registration Requirements form sets higher minimums: $250,000 bodily injury per person, $500,000 aggregate, and $100,000 property damage per occurrence and $100,000 aggregate. Private contracts often require more than either.
Why do roofers pay more for general liability?
Roofing often prices higher because of height exposure, completed operations risk, property damage severity, weather-related issues, and limited carrier appetite. Some carriers avoid roofing entirely or restrict the types of roofing work they will consider.
Does general liability cover employee injuries?
Generally no. Employee injury is what workers’ compensation and employer’s liability cover, not general liability. Texas is the only state where private employers may choose not to carry workers’ compensation. If you are a non-subscriber there is no comp system absorbing an employee injury, and an injured employee may bring a claim directly against the business, so the gap is yours rather than your GL policy’s. Coverage is compulsory for a governmental entity’s building or construction contract under Texas Labor Code 406.096, and private contracts frequently require it. Any particular claim is decided by the policy actually issued and the facts.
Does general liability cover my work truck?
Generally no. Business vehicle accidents are what commercial auto insurance is written for. General liability and commercial auto are separate policies, and which one responds to a given loss depends on the policies issued and the facts of the claim.
Is a COI the same as an endorsement?
No. A COI is informational evidence that the listed policies were in force when it was issued. It does not confer coverage and cannot change the policy. An endorsement is a policy form that can modify coverage terms once the carrier approves it. Many contracts require both a COI and specific endorsements.
Can I get same-day COI help?
If your policy is already active and the request is straightforward, same-day COI help may be possible. If the request requires new coverage, underwriting, or special endorsements, timing depends on carrier approval.
What is the fastest way to get an accurate quote?
Send your trade, revenue, payroll, subcontractor details, claims history, desired limits, and the full insurance requirement page from the contract or vendor portal. This helps the broker avoid guessing and route your account correctly.
Final takeaway
General liability insurance cost in El Paso, TX depends less on the city alone and more on what your business actually does. A lower-risk small business may fall near the $40 to $150 per month range, while contractors often need to budget $150 to $400+ per month. Roofers, GCs, excavation contractors, subcontractor-heavy operations, and prior-claim accounts may cost more.
The best move is not to chase the cheapest certificate. The best move is to match the policy to the contract, the trade, the carrier appetite, and the COI wording before the job starts.
ContractorsInsured.net is an independent contractor insurance broker, not a direct carrier. We help contractors compare coverage options where available, meet bid and compliance requirements, and move faster on COIs and common endorsements.
Working outside El Paso as well? See general liability insurance cost benchmarks.